





Loop Downgrades Apple As iPhone Rebound Shipment Hopes Slide
Apple shares are down about 1% in premarket trading in New York on renewed concerns about iPhone demand.
Loop Capital technology analyst Ananda Baruah downgraded Apple from "Buy" to "Hold," citing slumping expectations that the company will recover lost iPhone shipments next year and warning that skyrocketing memory chip costs could further squeeze profit margins.
Baruah lowered his 12-month price target to $330 from $370, nearly in line with Bloomberg-tracked analyst forecasts of around $334. The new target implies roughly 4% downside from the $343 share price cited in the note.
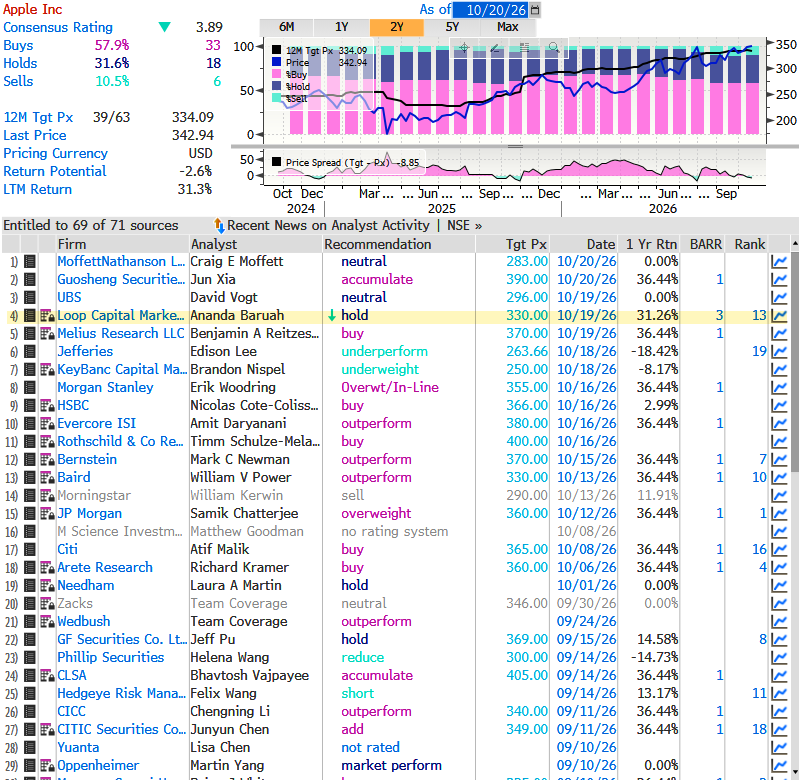
Baruah explained the reason for the rating downgrade:
We're downgrading AAPL to Hold from Buy and lowering our PT to $330 from $370 on new iPhone data from Loop Capital Supply Chain Analyst John Donovan (Latest AAPL ASP Tracker & Build Analysis – Reported Cuts Not True – Yet?) as our "normalized" EPS is reduced to $11.00 from $12.00 (and our new PT using an AAPL median P/E of 30x is $330.)
The gist is that when AAPL previously reduced its Sep Q & Dec Q iPhone unit ships by 10% we believed they would be in a position to make up many (if not most) of these units through CY2027 as the reductions were supply related (memory & processors) & not demand related.
This no longer appears to be the case. Further, while not the core aspect of our call today we acknowledge then potential for GM risk as memory costs continue to increase.
The revised forecasts also reflect much lower expectations for iPhone selling prices. For next year, the analyst slashed his average selling price estimate to $1,096 from $1,235 and reduced projected iPhone revenue to about $285 billion from $315 billion.
He expects total 2027 revenue to reach $539 billion, down from $569 billion, and earnings of $9.76 a share, compared with his previous $10.11 estimate.
For the December quarter, Baruah forecasts 79 million iPhone shipments, below the consensus estimate of 85 million. He forecasts iPhone revenue of about $88.7 billion for the quarter, below Wall Street expectations of roughly $93 billion.
Baruah's note, published on Monday, builds on soft iPhone demand cited by analysts at Jefferies and other desks. There was good news last week on Duo demand, as the flurry of preorders outstripped launch inventory, pushing some orders out until January 25. But premium handsets priced at $1,000-plus and $2,000-plus are still too expensive for mass adoption. Apple's Tim Cook learned that the hard way with the $3,000-plus, goofy-looking Vision Pro.