


Hung, Drawn, And Third-Quartered: Roll On Q4
By Michael Every of Rabobank
Today ends Q3, which has been a shocker even in a year of major market shocks.
Wars dragged on and spread. Russia-Ukraine saw energy sites hit and hybrid attacks against Europe increase. Saudi Arabia, not Iran, is now under missile fire and both oil exporters are partly blockaded. France gave the first sign of getting dragged into the war, which conflated more with Russia-Ukraine. A US-China summit suggested détente but news that families of Chinese AI workers can no longer leave the country suggested it’s minus a ‘te’ and an ‘e’ - and China just opened an airbase in Laos. Canada floated joining the EU and fighting a US invasion like the Taliban, as Greenland became a permanent US security protectorate with Ottawa’s approval. Argentina still wants the Falklands back, which London can no longer project power towards as in 1982, and as it continues to try to give away other strategic territory against strong US objections.
AI saw a series of remarkable headlines: technological breakthroughs, market meltdowns and melt-ups, and new political pushbacks. Perhaps the highlight was the upcoming Anthropic IPO telling would be shareholders that AI may pose an “existential risk to humanity.”
Western stocks had a steady Q3 until recently. With today’s session still to come, the S&P is +2.3% q-o-q vs. +14.9% in Q2 and -4.6% in Q1. The Dow -1.9% vs. +12.9% and -3.6%, the Nasdaq +2.2% vs. +21.4% and -7.1%, Eurostoxx are flat vs. +13.4% and -3.6%, the FTSE +1.3% vs +3.2% and +2.5%, but the Nikkei is -6.5% vs. +37.2% and +1.4%, the Shanghai composite -6.4% vs. +5.2% and -1.9%, and the Indian Sensex -5.2% vs. +6.3% and -15.6%.
Q3 saw the most dramatic up move in bond yield so far this year. With today yet to come: US 2s are now 4.90% (+72bp q-o-q), 10s 5.24% (+76bps), and 30s 5.57% (+60bps), the highest since 2002; Bund 2s are 3.29% (+76bps), 10s 3.62% (+76bps), and 30s 3.95% (+53bps); OATs 2s are 3.64% (+94bps), 10s 4.81% (+116bps), and 30s 5.39% (+93bps); Gilts 2s are 4.91% (+76bps), 10s 5.41% (+65bps), and 30s 5.92% (+44bps); JGB 2s are 1.96% (+59bps), 10s 3.11% (+43bps), and 30s 4.20% (+26bps).
Q3 didn’t just drop hopes of ‘lower for longer’ but doused them in scarce diesel and set fire to them. In Q1, we got just one rate hike from a G20 central bank, the RBA. In Q2, we got four, the RBA, ECB, BOJ, and Bank Indonesia. In Q3, we got the RBA (who just hiked again yesterday and are seen doing so again in the new year), the ECB, the BOJ, plus the Fed – and the issue is how much more might be needed there and elsewhere.
FX markets were also caught on the hop if expecting a weaker USD, as is so often the case, with a notable exception with huge implications for other markets. EUR/USD is around -1.1% q-o-q and GBP/USD had an unexciting Q3 while the DXY is slightly up right now. However, there was huge action in USD/JPY in the opposite direction that may carry through to the Yen Carry Trade if it carries on. EM FX are notably also starting to slip against the dollar again with the exception of CNY, which is a ballgame unto itself.
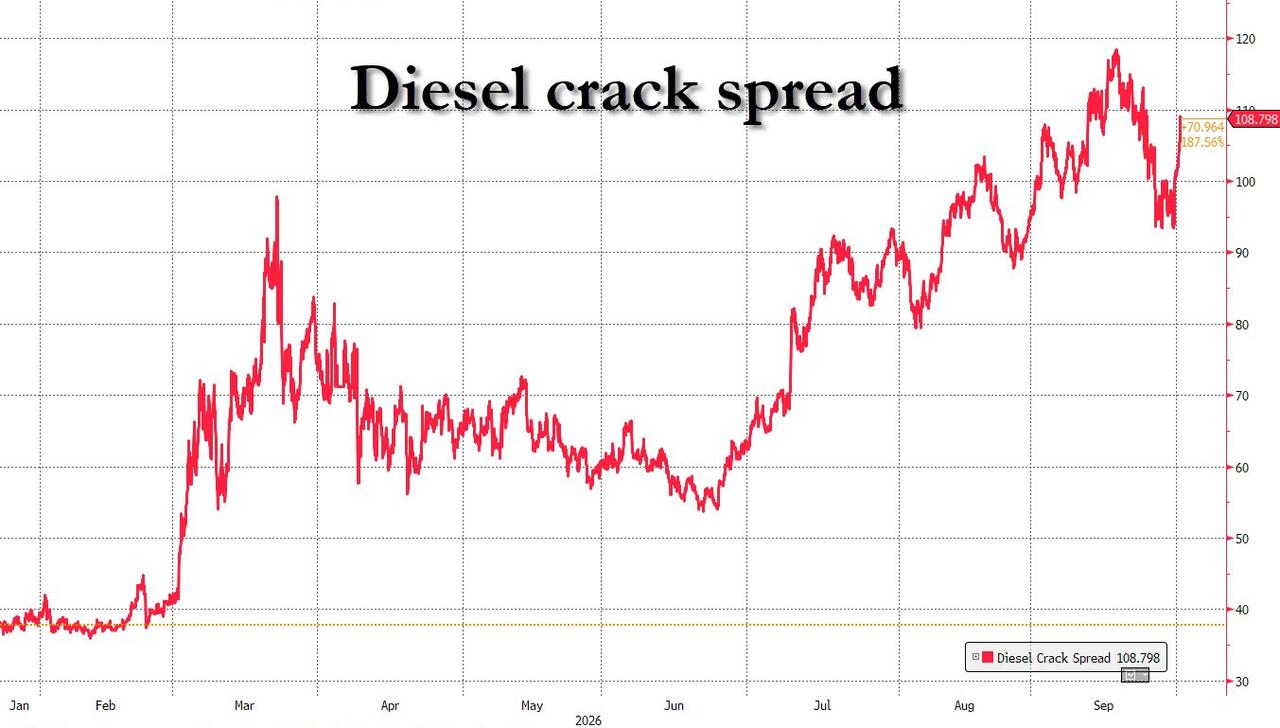
Brent oil is $104 right now, well up over a Q3 it started at $73 while the 3-2-1 crack spread is $62 vs. $17, which is what matters more, so we moved from an effective total of $90 to $166. The FT today notes that oil prices and US Treasury yields are in tightest relationship since 1990 – you mean during the late Cold War, when it was all about geopolitics at core? What a surprise!
So, what goodies will Q4 bring?
Geopolitics is on a knife edge between efforts to bring peace and a dynamic leading towards more, and more widespread war. Beyond Hormuz and the Red Sea, Iraq today sees US troops withdraw, as Ethiopia blames regional rivals for unrest with a risk of conflict spillover into the Horn of Africa, and Israeli PM Netanyahu claims indications of an attack plot by ‘enemies’ ahead – which the opposition leader, briefed on it, has publicly decried. Concerns are Russia-Ukraine could escalate into outright provocations vs. Europe and NATO, as the EU’s military mobility plan faces a €100bn bill and Ukraine is pushing for “bold action” on Russian assets to plug a $78bn defence spending gap in 2027: Politico notes ‘Tax cuts, handouts and blind hope: Europe finds few tools to fight a coming energy crunch.’ In Asia, China and Japan are verbally clashing despite some signs of an attempted reset, as Japan’s defence chief again brought up the “nuclear taboo” and the business press reports that ‘China strengthens position for Taiwan conflict with mobilisation law.’
In AI, Trump and AI CEOs just signed a voluntary safety pact and backed data centre expansion, but Sam Altman said OpenAI will delay its IPO until it overcomes safety concerns – regardless, tech supply chains continue to see unprecedented, dare I say wartime(?), demand boom conditions. The UK AI minister just admitted the country doesn’t “currently have a position where we can build superintelligence” as it’s “illegal to do so” in terms of regulations and the power demand required. Europe is meanwhile discussing an EU-wide digital levy to generate up to €25bn annually for the next budget, which will infuriate the US (and which Germany and other major contributors reject as outlined, demanding hundreds of billions of cuts).
Indeed, geoeconomics is on a knife-edge too. Will the EU initiative a trade war with China in Q4 via an expanded Anti-Coercion Instrument or resign itself to higher flows of Chinese imports in higher value-added sectors, so less local industry? Ford's CEO just urged US caution on Chinese automakers and said for Europe it’s “too late.” But could China then choke Europe on rare earths? Yesterday, the US ambassador to China posted that "Back in April of last year, China put the export regime process in place for rare earth elements and magnets. Then, on October 9th, they weaponized that by expanding that to the entire world. Now, they've weaponized it even further by escalating to the point where they make any diversification efforts away from China as a criminal offence...”
Politically, we may face an October surprise ahead of November US midterm elections where talk is of a Blue Wave (like the Red Wave that didn’t materialise in 2022). Either way almost everywhere the trend is to populism of the left and right. That’s clear in Europe, and the UK just saw PM Burnham promise PR, rejoining the EU, and reindustrialisation, without tariffs or industrial policy, which the Guardian called a “radical progressive plan to help Britain ‘rise again’’ yet had to add was “a clear vision for Britain – but not for how it fits into a troubled world.” Equally, the Wall Street Journal today notes ‘Americans Want Populist Policies That Defy Traditional Political Labels’, where their survey finds broad support for caps on prescription drug prices and strong border security. In short, nobody wants the policies being sold as the solution to high inflation.
So, what’s your guess for Q4?