





META Erases Most Afterhours Gains After CFO Warns "Significant Investment" Will Raise Serving Costs
Update: We concluded our prompt earnings wrap (below), by saying that the question now is whether Zuck will scare investors on the call by noting that capex may raise much more." Well, CFO Susan Li did not help the case saying that “Muse's compute intensity means that expanding its user base will require significant investment, and we expect total serving costs to rise. At the same time, we expect to improve compute cost efficiency by more than 10-fold over the next year."
Translation: much more capex spending is coming, as in MUCH more, and not just the record $59BN implied by the 2026 capex guide...
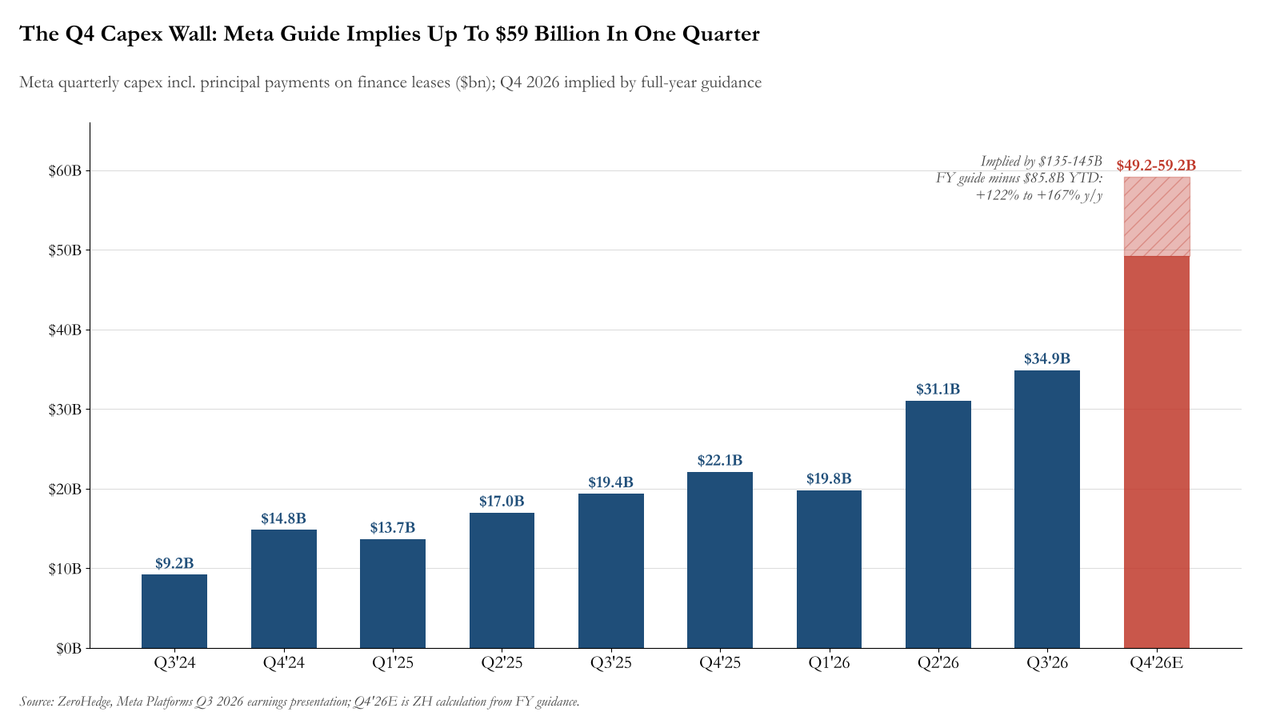
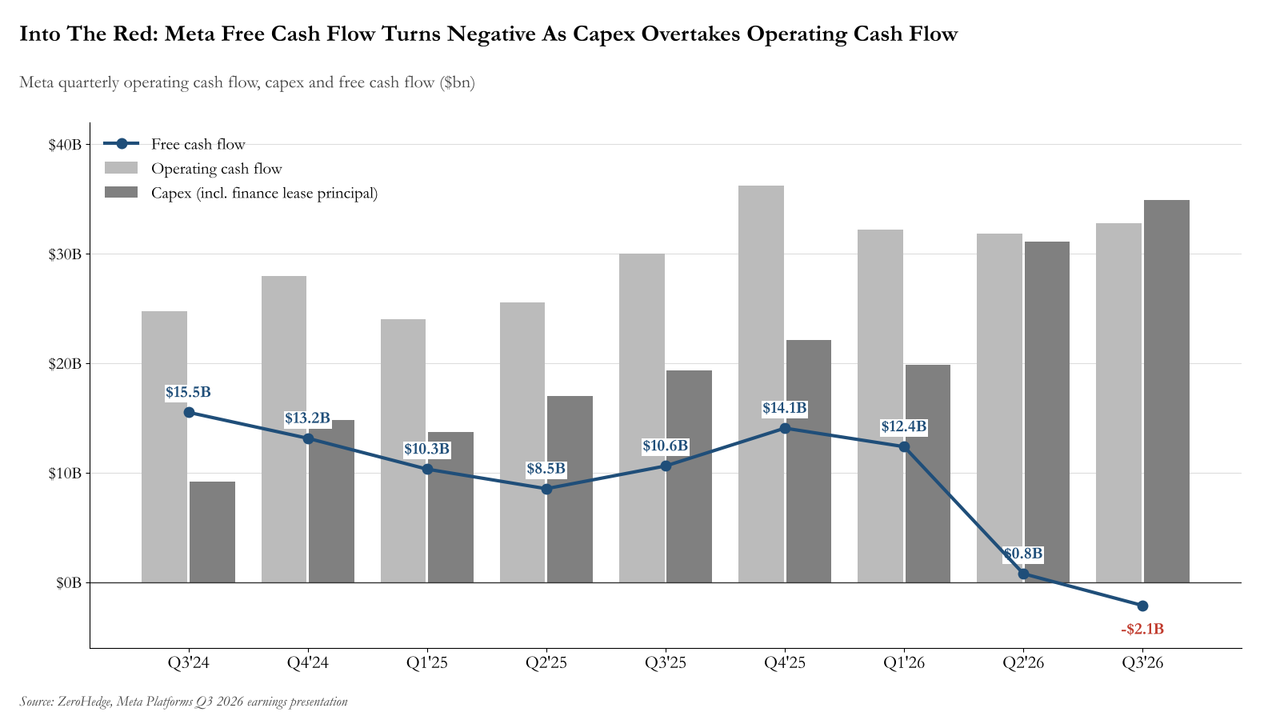
... but much more in 2027 and beyond (sadly the company no longer provides guidance beyond this year). Which is a problem for a company which just joined Amazon in watching its free cash flow turn negative.
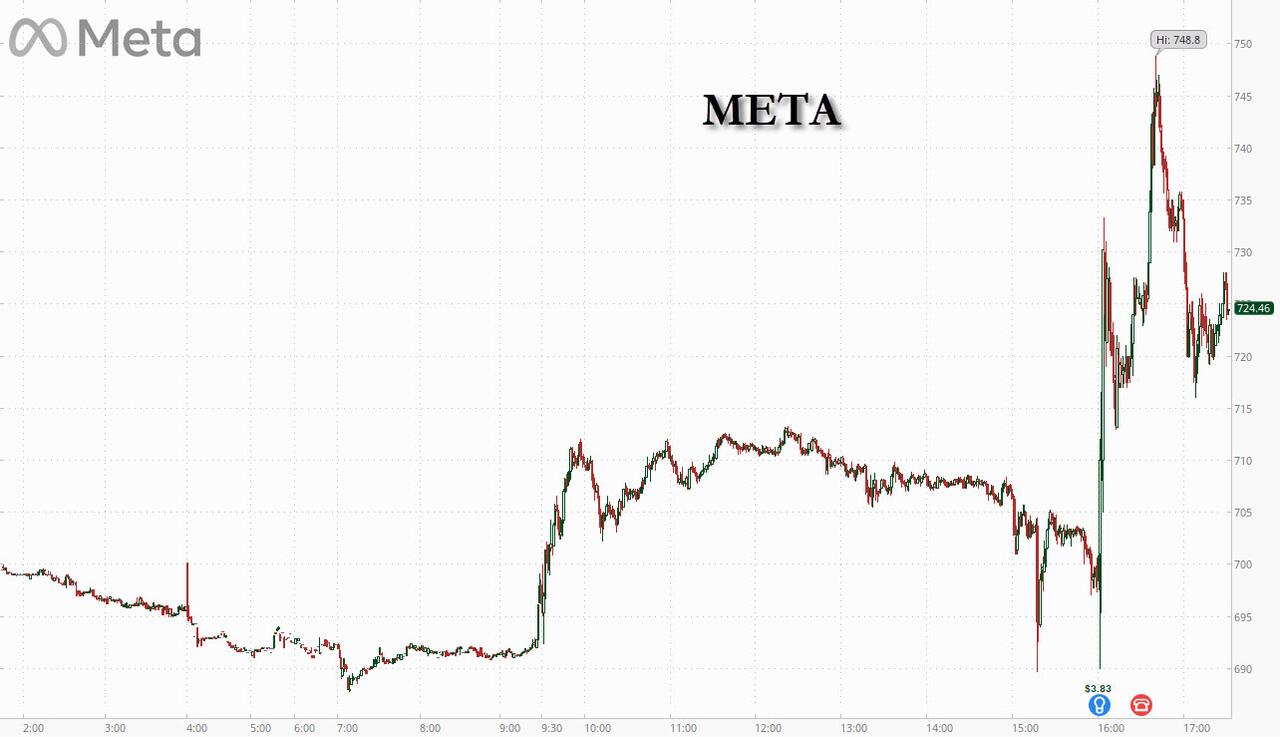
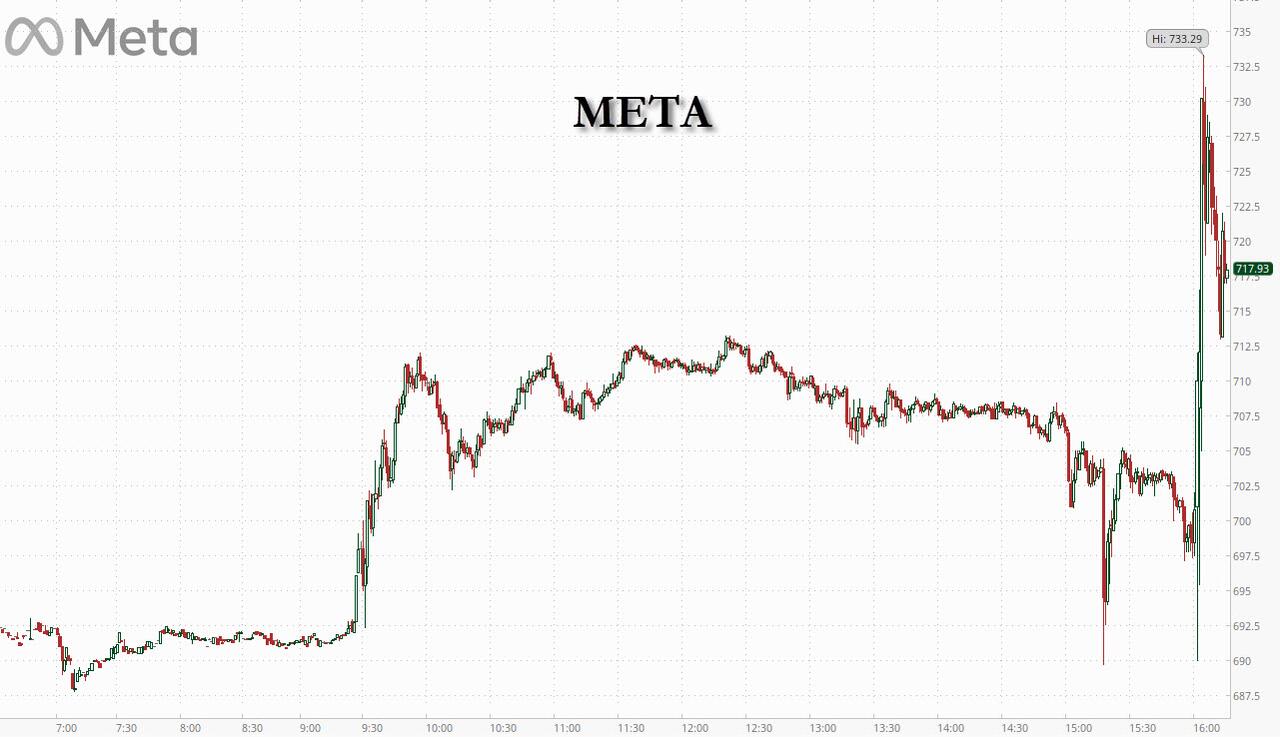
The stock did not like it, and after hitting a session high of $748.8, it has erased almost all after hours gains.
* * *
Earlier
In our preview of Meta's earnings, we laid out expectations...
- Revenue estimate $63.32 billion (Bloomberg Consensus)
- Advertising rev. estimate $61.82 billion
- Family of Apps revenue estimate $62.75 billion
- Reality Labs revenue estimate $517.7 million
- Other revenue estimate $1.1 billion
- Operating income estimate $20.28 billion
- Family of Apps operating income estimate $23.96 billion
- Reality Labs operating loss estimate $5.21 billion
- Operating margin estimate 32.5%
- EPS estimate $3.56
- Ad impressions estimate +12.3%
- Average price per ad estimate +11.2%
- Average Family service users per day estimate 3.66 billion
... and also sketched a setup of what to expect from earnings:
- expectations at 9/10,
- positioning at 8/10,
- Mag 7 exposure at a record,
- an implied move that Goldman calls cheap,
- a buyside bar for 2027 spending that's $50 billion above the Street,
- a product whose growth may already have peaked, and...
- an equity raise that the majority of the buyside expects as soon as the stock lets it.
Bloomberg points out that at 19x forward earnings, Meta is the second-cheapest Mag 7 stock after Nvidia. Well, it probably should be.
The bull case is that Zuckerberg beats, guides Q4 to $75 billion, drops a Muse DAU number (although with Claude just launching its own agents, it is about to get crowded) and keeps 2027 vague, and the stock grinds to $800 and the equity offering. The bear case is that he does all that and then says the words "notably larger" about 2027 capex. Judging by Meta's last two Q3 prints (-4% and -11% last October), and the last two prints overall (-9% and -8%), we know which one the tape has favored lately: the market keeps paying Meta for products and charging it for the bill.
With that in mind, here's what Meta reported moments ago for its Q3 quarter:
- Revenue $64.60 billion, +26% y/y, beating estimate $63.33 billion
- Advertising rev. $63.06 billion, +26% y/y, beating estimate $61.85 billion
- Family of Apps revenue $64.16 billion, +26% y/y, beating estimate $62.75 billion
- Reality Labs revenue $443 million, -5.7% y/y, missing estimate $517.7 million
- Other revenue $1.10 billion, +59% y/y, in line with estimate $1.1 billion
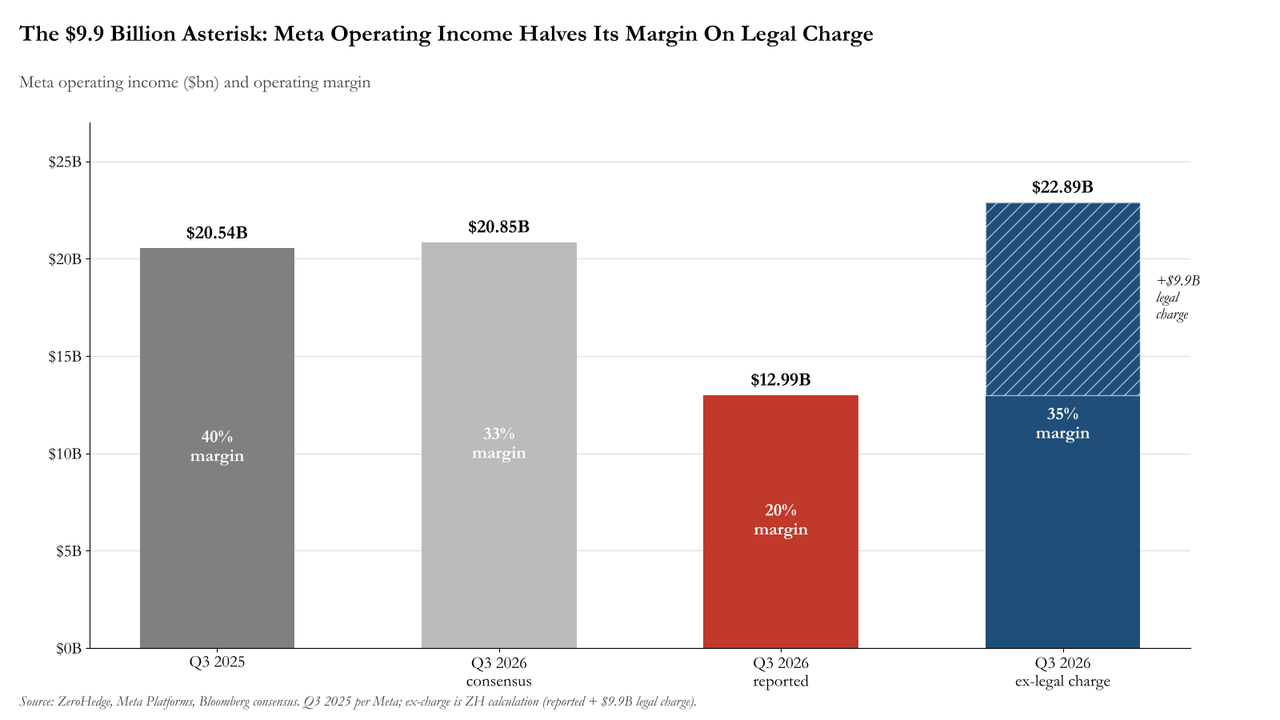
Operating margin 20% vs. 40% y/y
- Operating income $12.99 billion, -37% y/y, badly missing estimate $20.85 billion
- Family of Apps operating income $17.12 billion, -31% y/y, beating estimate $23.3 billion
- Reality Labs operating loss $4.13 billion vs. loss $4.43 billion y/y, estimate loss $5.13 billion
- EPS $3.83 vs. $1.05 y/y, beating estimate $3.57
- Operating margin 20% vs. 40% y/y
Here is how the numbers came relative to expectations:
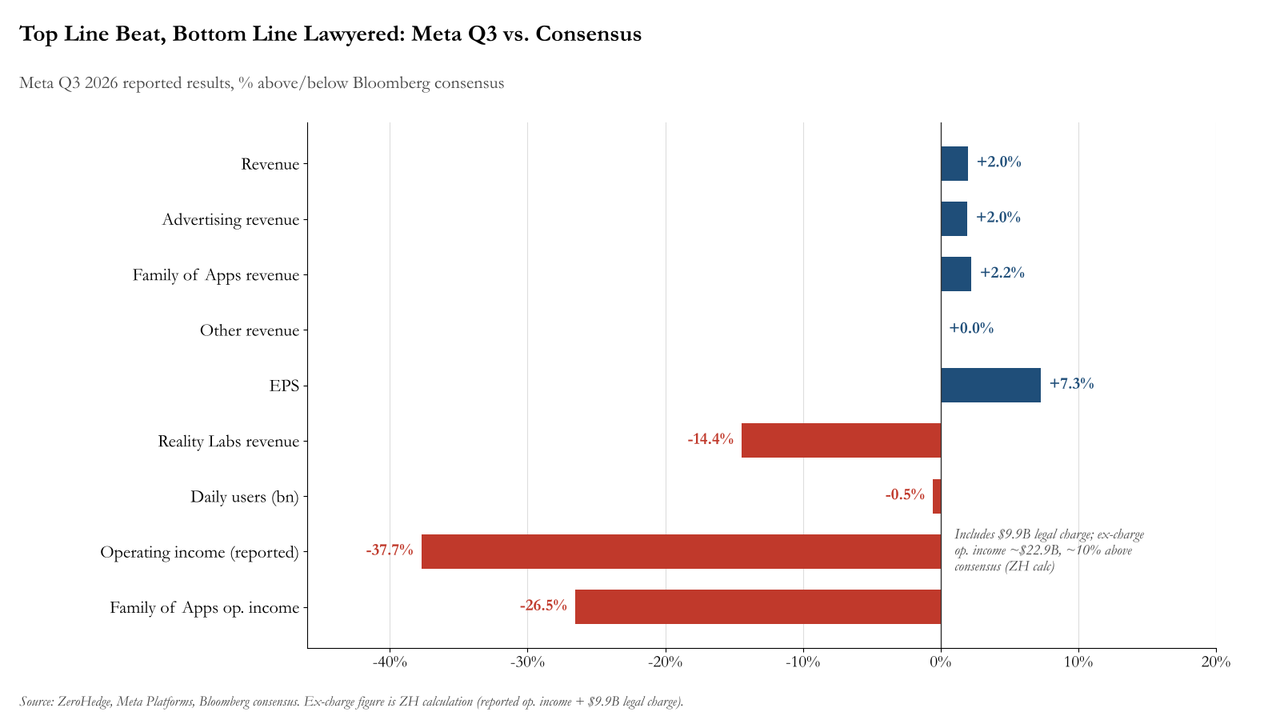
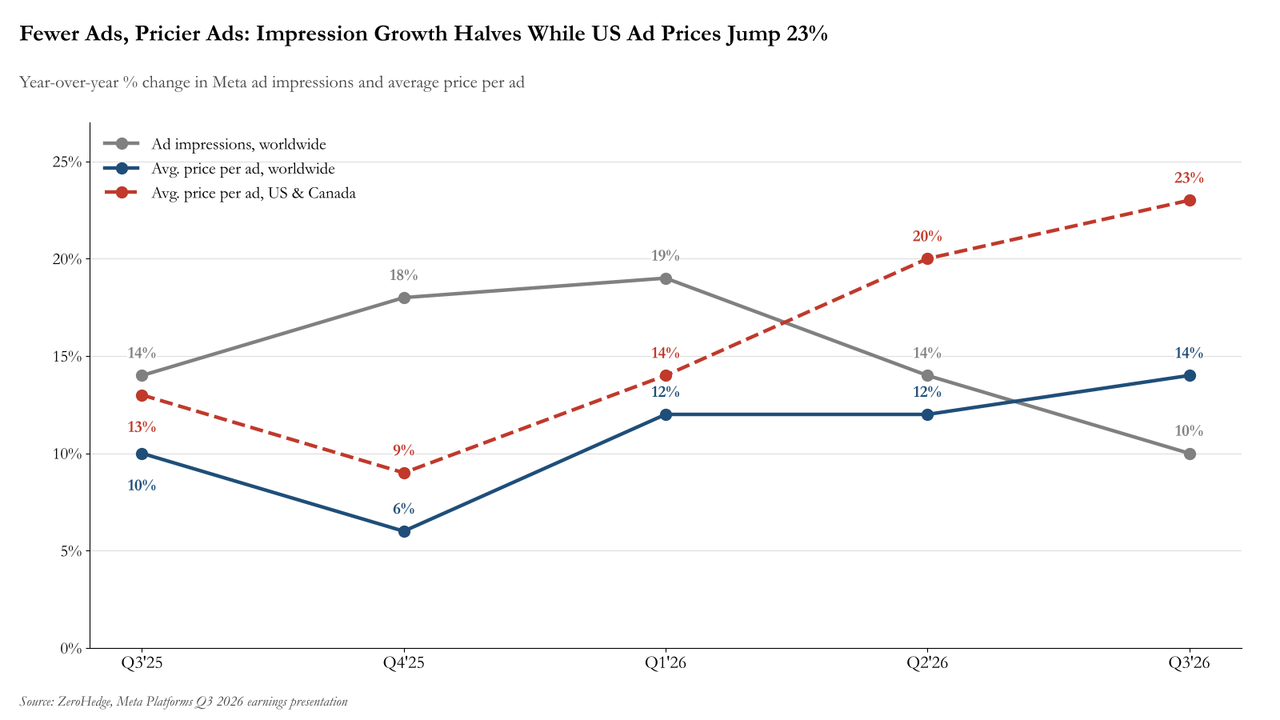
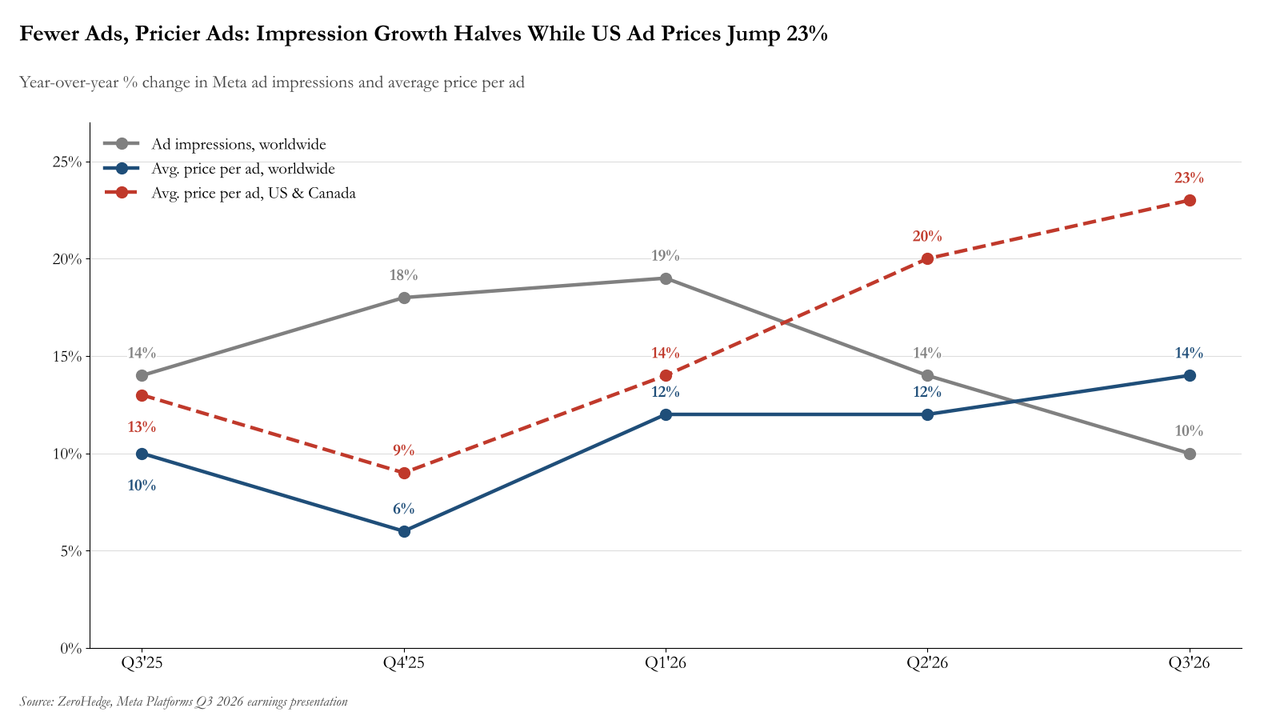
There was some notable weakness in the company's core ad business: while average ad prices rose, impression growth actually collapsed.
- Ad impressions +10% vs. +14% y/y, estimate +12.3%
- Average price per ad +14% vs. +10% y/y, estimate +11.2%
A few more highlights from the quarter:
- Meta Establishes New Non-Voting Class C Common Stock
- Meta Lifts Expense Outlook to Incorporate $9.9B Legal Charge
Looking ahead, Meta shared the following Q4 revenue guidance: $73-76BN, vs sellside estimates of $73.6BN; recall in our preview we noted that the Street is at ~$73.5 billion (+24% FXN), with JPM's Schilsky saying investors "will tolerate no more than a 1-point FXN decel on the top end of the guidance range," so the expected guide is $72-75 billion. Deutsche hears a slightly lower top end, "roughly $74-74.5bn."
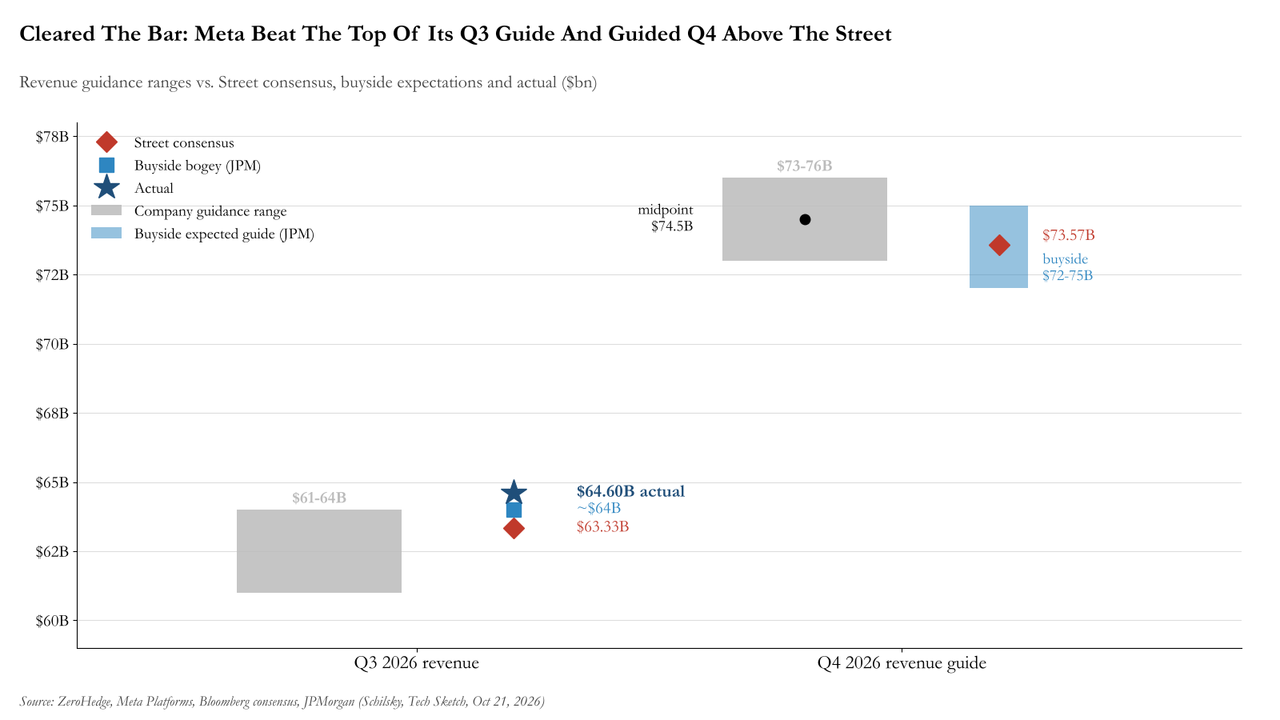
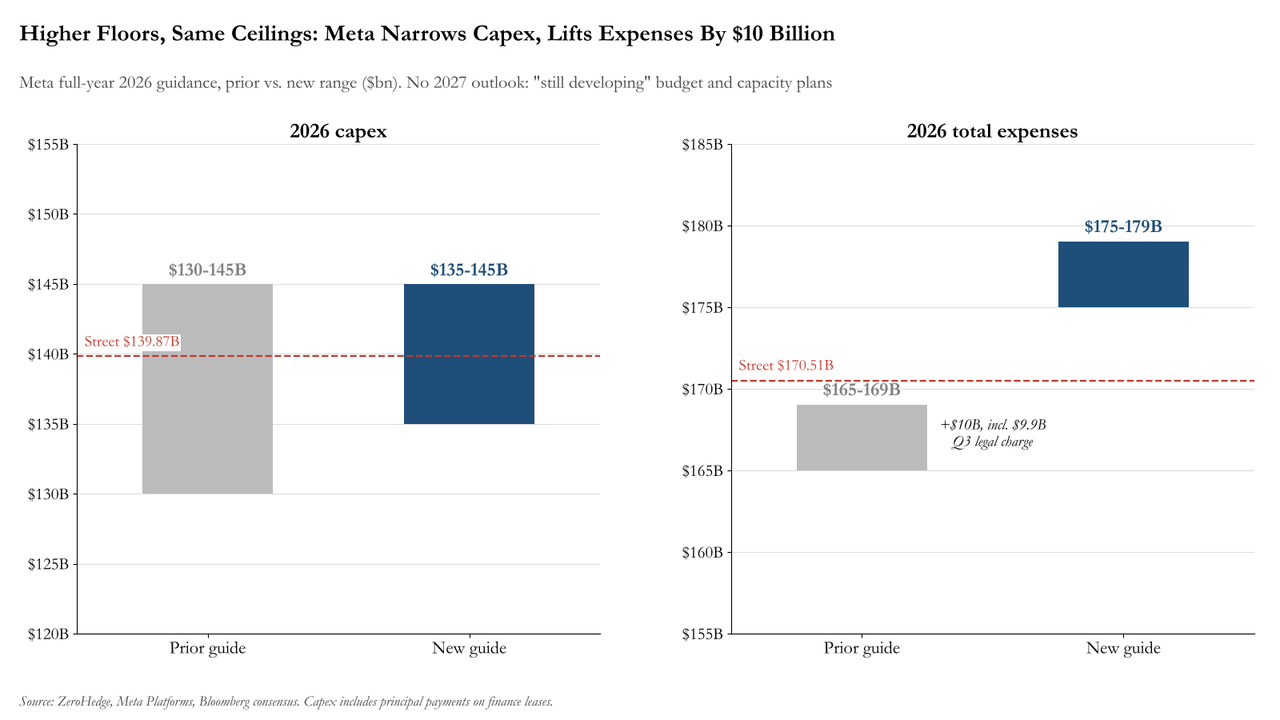
So Q4 guidance roughly in line with expectations... however that takes place at the expense of another capex increase, with Meta now expecting capex in the range of $135-$145, up from $130-$145 billion.
Doing some quick math here, we find that as a result of underspending on capex in 2026, META now has to spend as much as $59BN in one quarter, an absolute record considering its previous record was $34.9bn... this quarter. It will be interesting to see what META spends all this money on.
But wait, there's more because remember capex is just half the story since Meta can book data center spending either as capex (building it) or opex (leasing it from the likes of Crusoe), JPM said to watch the sum: "Buyside Consensus for 2027 Opex + Capex is in the range of $435B to $475B – that's a midpoint of $455B."
In this context, Meta raised its expense outlook to incorporate the $9.9 billion charge related to legal proceedings recognized in the third quarter, and now expects full year 2026 total expenses to be in the range of $175-179 billion. We will circle back once we calculate what all this means for the company's blended all in opex and capex for 2027 but it will be big.
Some more from the company:
- Meta Establishes New Non-Voting Class C Common Stock
- Meta Lifts Expense Outlook to Incorporate $9.9B Legal Charge
- "Excluding the third quarter legal charge, we continue to expect 2026 operating income to be above 2025 operating income."
- "We now expect full year 2026 total expenses to be in the range of $175-179 billion."
- "We expect fourth quarter 2026 total revenue to be in the range of $73-76 billion."
To the last point, news broke today that Meta plans to introduce a new class of non-voting stock that it could use to fund its heavy spending on artificial intelligence, according to a Semafor report. The plan could be announced as soon as Wednesday during the company’s quarterly earnings report, the publication said, enabling Meta to use the stock to fund acquisitions and AI spending without diluting CEO Mark Zuckerberg’s control of the company.
Following the earnings release, the initial stock reaction was muted but shares have now picked a direction - the stock was up 4% after hours, before easing back on the gains, and up about 2% at last check.
The question now is whether Zuck will scare investors on the call by noting that capex may raise much more.