


"Moving The Goalposts": BofA Downgrades Nike, Slashes Target As Turnaround Story Delayed
Nike shares fell 2% in New York premarket trading after BofA retail analyst Lorraine Hutchinson downgraded the world's largest athletic footwear and apparel company, warning that its "turnaround is taking longer" than expected. With shares trading at 2014 levels, the downgrade adds new woes to a recovery story that might not materialize until 2028.
In the report published earlier today, titled "Moving the goalposts," Hutchinson downgraded Nike to "Underperform" from "Neutral" and cut her price target to $30 from $47, implying 17% downside from Thursday's close of $35.99.
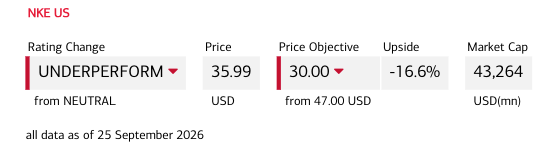
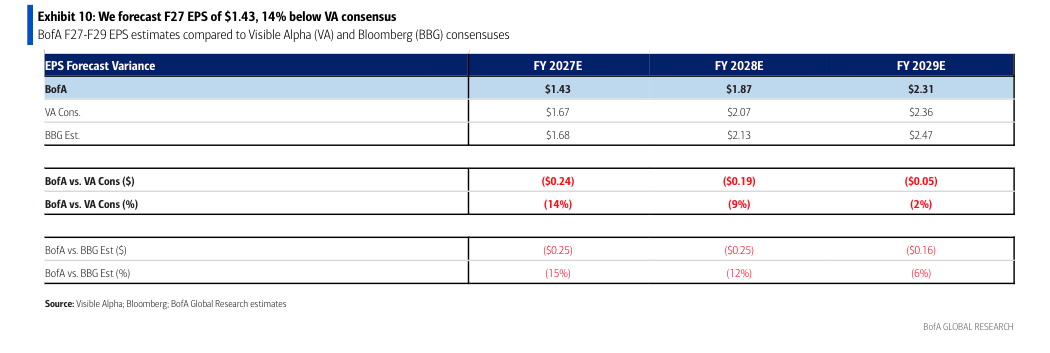
Hutchinson now expects a sales decline through 2027, abandoning her earlier call for a 1H27 recovery and pushing the turnaround into 2028. She cut fiscal 2027 and 2028 earnings estimates by 11% and 12%, respectively. Her 2027 forecast of $1.43 a share sits roughly 14% below Visible Alpha consensus.
She added color:
Risks are rising, downgrading to Underperform
We see downside risk to EPS estimates and valuation as Nike's innovation continues to be overshadowed by a pressured classics business, while category and macro pressures build. We are cutting F27E/F28E EPS by 11%/12%; we now expect negative sales growth through F27E versus our prior view of a Spring inflection. Our F27E EPS is 14% below VA consensus. The dividend payout ratio is over 100% and, as a result, we are reducing our income rating to 8 (same/lower) from 7 (same/higher). Our $30 PO (was $47) is based on a 16x P/E (was 22x), now aligned with the peer average.
Wholesale momentum should slow as sell-through lags
NA wholesale has been an area of strength, growing 14% in F26 vs. flat total sales growth. In some instances, sell-through is lagging sell-in due to declines in classic styles and new launches that are missing expectations. This puts forward order books at risk as retailers become less willing to make a bet on newness until success is proven. We see progress slowing in 2Q as the business laps 24% growth, and remaining challenged in 2H as the current issues pressure Spring orders. We model NA wholesale sales declines beginning in 2Q through the rest of F27.
China reset faces a tougher demand backdrop
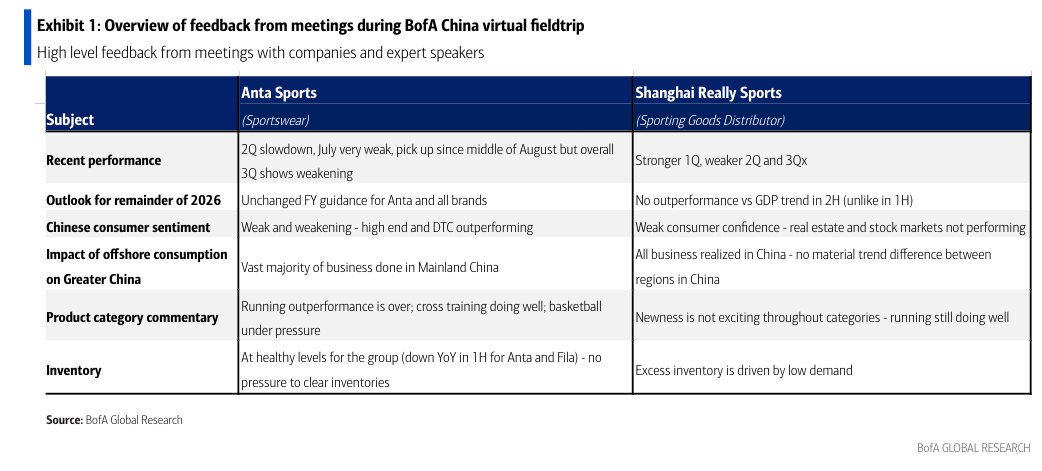
China is in flux, and Nike's reduction in partner online sales will likely cause promotional pressure through 2Q. After that, Nike is expected to present the brand more cohesively online. Competition is intense; the quest for newness is higher than ever, and we see risk that sales decline at least through F27. BofA's Luxury Goods team's China fieldtrip takeaways included weak sports demand, with product newness not resonating, moderation of running outperformance, and excess inventory driven by low demand.
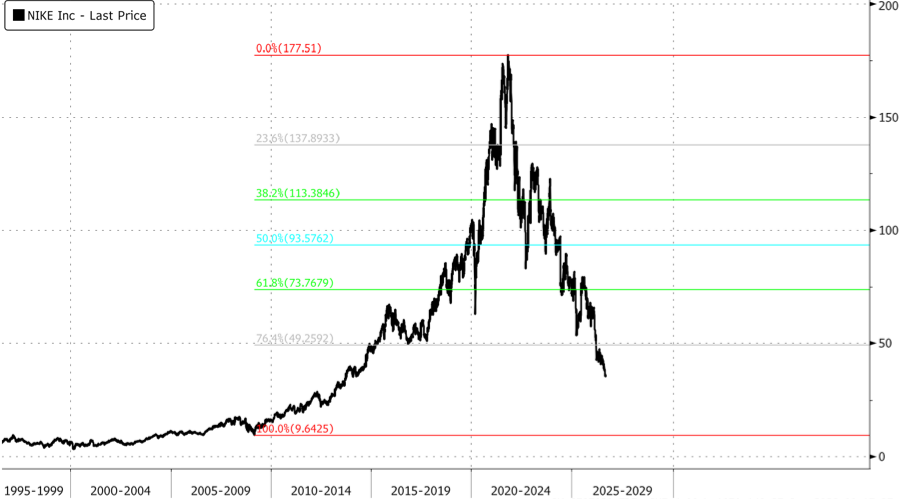
Despite Nike's 44% year-to-date bear market, Hutchinson said it's "unlikely that the stock will hold a premium multiple in the face of further EPS cuts. We see some green shoots on product innovation, but those have been dwarfed by weaker larger casual categories."
She added, "We think the multiple could compress as the turn is pushed to F28."
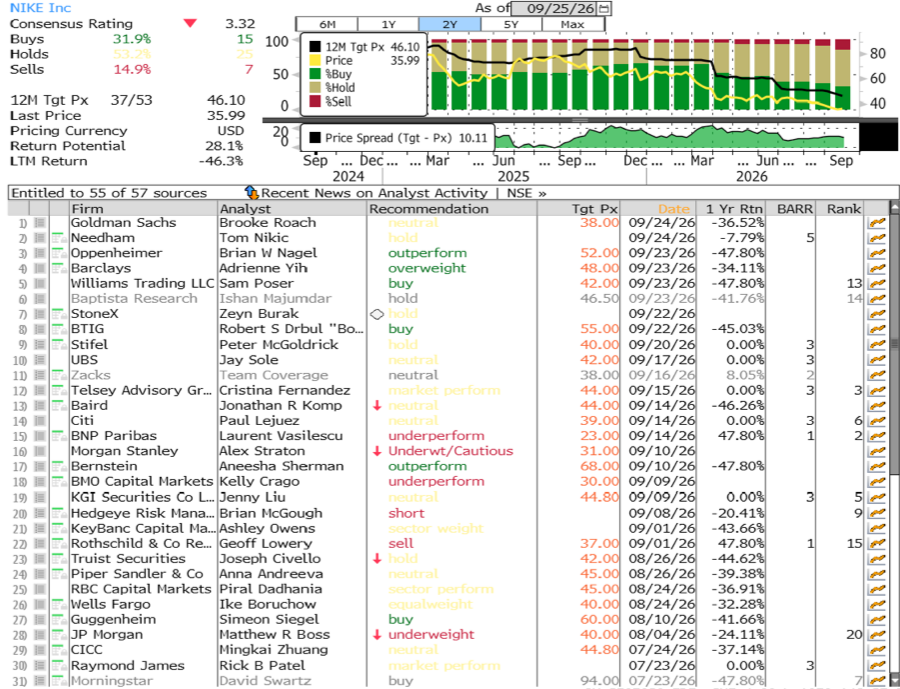
According to Bloomberg data, there are 15 "Buy" ratings, 25 "Neutral" ratings and 7 "Sell" ratings on the stock, with a 12-month price target of $46.10.
The stock is already down 80% from its 2021 high of $177. Where stabilization occurs and halts the vicious bear market remains to be seen, but it could materialize next year as Wall Street analysts see a turnaround ahead. Yet BofA analysts have pushed that expectation back to 2028.