


Russia Just Put the World's Uranium Supply at Risk
Russia has temporarily banned the export of sulphuric acid until the end of the year, to secure supply for its own industrial and fertiliser producers. It sounds like a niche chemicals story. It is not. It lands directly on the world's largest uranium producer, Kazakhstan, and its reliance on Russian acid.
Why the acid ban matters for Kazakh uranium
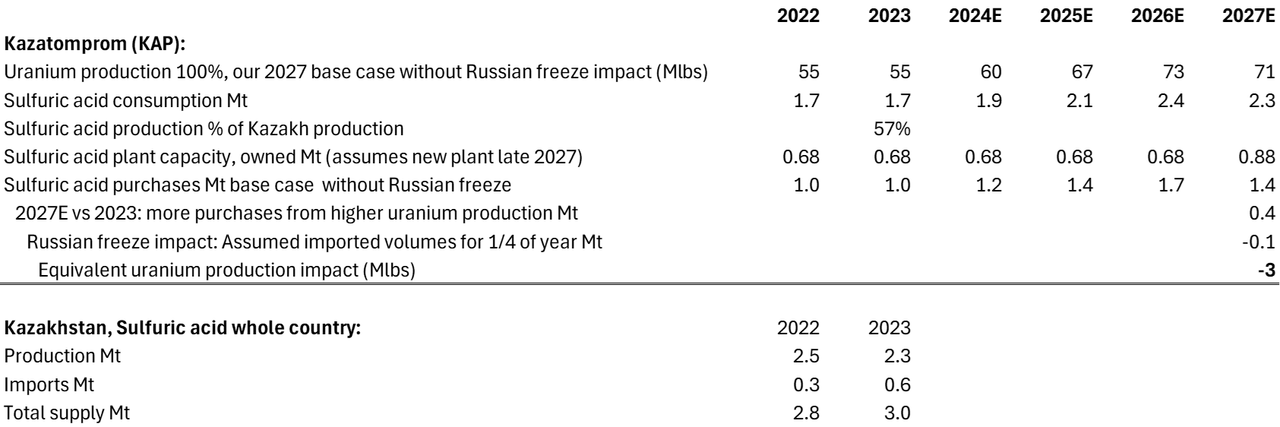
Kazakhstan is a notable producer of sulphuric acid, at around 2.4 Mtpa, but the country runs a deficit, importing roughly 20% of its annual needs, mainly from Russia. Sulphuric acid is the binding input for the in-situ leach method Kazakhstan uses, so acid availability directly constrains how much uranium the country can produce.
Kazatomprom recently delayed the start-up of its new 0.8 Mtpa acid plant to late 2027 or early 2028. Until that plant is running, the company relies on external acid purchases of around 1.5 Mtpa to sustain production of c70-75 Mlbs. Its own acid production is about 60% of the Kazakh total, and we estimate around 0.3 Mtpa of its acid needs are met from imports.
Assuming Kazatomprom has already secured a majority of its imported acid for next year's production, the residual exposure is manageable but not trivial. If no intergovernmental arrangement is reached to keep Russian acid flowing to Kazakhstan, we estimate the ban could reduce Kazatomprom's 2027 production by around 3 Mlbs, or roughly 4%. We still await the company's 2027 production plans.
Kazatomprom and Kazakh sulphuric acid requirements, and estimated Russian freeze impact
Source: Asymmetric Research, inbusiness.kz, Kursiv Media
The waiver question, and the Uranium One angle
The Russian resolution allows exceptions: exports can proceed where approved by the Russian authorities, or under intergovernmental agreements and international transit arrangements. On the face of it, Kazakhstan is the kind of counterparty for which such a waiver would make sense. The two countries are closely tied in the nuclear fuel chain, and those ties have if anything just deepened.
In late August, Kazatomprom disclosed an agreement to sell natural uranium to Uranium One Group, the Rosatom entity that operates Russia's foreign uranium assets and is itself a shareholder in several of Kazatomprom's key joint ventures, with physical delivery into Russia's Siberian Chemical Plant. The agreement is to be put to Kazatomprom shareholders at an Extraordinary General Meeting, with voting concluding in early October. So at the very moment Russia is restricting acid exports, it is deepening its uranium relationship with Kazakhstan. That interdependence makes a waiver for Kazakh acid supply look logical.
On balance we think it would be reasonable to expect some form of agreement to be reached, given the depth of the relationship. But we would not assume it, and until it is confirmed the c3 Mlb risk to 2027 production stands.
In any case, the episode reinforces a theme we have made repeatedly: the time of cheap uranium is over. Kazakh costs are on fire and acid shortages persist.
The more important point for Kazakhstan, and one we think the market is missing, is the strategic uranium reserve set out in the country's Nuclear Industry Development Strategy, announced in April. That is the real game changer for the Kazakh supply outlook, and we think it will limit production there meaningfully over time. We covered it in detail in our earlier reports on the sector.
Uranium equity valuations
[...]
This article is based on research originally published on Asymmetric Research. Continue reading, including where we now see value across the uranium equities and how we are positioned, at: asymmetricresearch.substack.com
***
Disclaimer: This article is for informational purposes only and does not constitute investment advice or a personal recommendation. Past performance is not indicative of future results. The value of investments can go down as well as up. Uranium and related equities are highly volatile. Readers should seek independent professional financial advice before making any investment decision. The author and Asymmetric Research may hold positions in uranium and related equities.