


Why America’s wartime borrowing, rising real yields and China’s gold strategy may be forcing the Treasury into an impossible balancing act.
We wrote last month on Goldfix about the curious actions of the Treasury Secretary intervening in a bond market on the pretext of improving liquidity where no such enhancement was needed. So far, this month he continues to challenge markets with his rhetoric.
For example, as reported by Fortune on 9th September he stated, “I have asymmetric information. I am the house now. You can bet against me if you want.” We find it intriguing that so much bravado should be shown for such a small intervention. Could there be more to it than just getting the most bang for your buck? Then, on the 10th the Treasury stated that it would buy up to $6bn. Given the bravado, the market expected $10bn. Yields are breaking out. Why is the Secretary cornering himself? What is he concerned about? Let us attempt to fill the void.
Chart 1
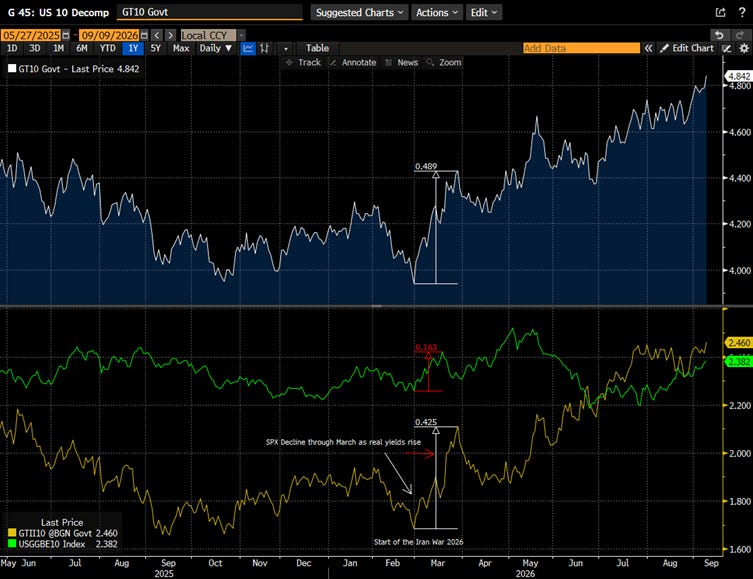
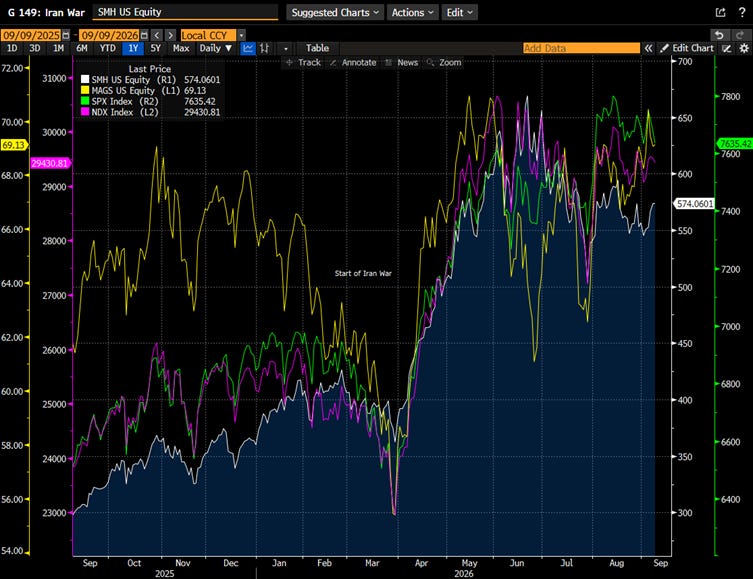
We isolate this time frame as this move coincided with a sell-off in US equities. Whether it was the S&P 500, the Nasdaq, Semi-Conductors or the Mag-7; all declined during this period – see Chart 2.
Chart 2
While narratives have later emerged from April onwards as the driving forces behind the ongoing expansion in real yields (that are coincidentally AI and US Equity bullish): competition for capital from Hyperscalers; a capex boom from AI buildout; or future productivity gains, this was something different.
- 10y yields increased, driven by real yields. Inflation spreads were well behaved.
- US Equities broadly declined.
- The US Dollar rallied.