


Westinghouse Targets $50Bn IPO, Six Times Its 2023 Price. What's The Upside Left?
Bloomberg reported last week that Westinghouse is targeting a valuation of more than USD 50bn in its coming US IPO, with a public filing as soon as October. We flag it because it validates the analysis we published on 3 August, and puts a number on it that sits within the range we set out.
When we published our valuation of Westinghouse, we set out a base case fair value of more than USD 40bn (precisely USD 43bn), a bull case of USD 85bn, and a conservative case of USD 26bn. For context, Brookfield and Cameco acquired the whole of Westinghouse for around USD 8bn in 2023. The reported IPO target of over USD 50bn now sits above our base case and toward our bull case, more than six times the acquisition price of less than three years ago.
We set this out not to take a victory lap on a deal that has not yet priced, but to make a simple point about how we work: we build the numbers from scratch, we set out our assumptions in full, and we put the reasoning on the record beforehand.
How we got there
Our valuation rested on three things. First, the pipeline. Cameco disclosed in its Q2 materials that Westinghouse could capture up to 91 of its flagship AP1000 reactors, around 105 GW, through to 2040, along with the economics of each build and the long-tail service revenue that follows. Second, method. Rather than value the headline backlog at face, we ran a probability-weighted DCF: assigning a probability to each project bucket actually proceeding, an expected market share, and the operations and maintenance (O&M) contracts that follow each reactor for decades.
For full transparency, our base case, which produced the USD 43bn figure, rested on the following assumptions:
- A 60% chance the full US build goes ahead, with Westinghouse winning all of it.
- Full probability that the 3.5 GW of new nuclear capacity in Poland goes ahead and is built by Westinghouse.
- That the 66 GW of other large design contracts have a 25% probability of going ahead, with Westinghouse taking a 40% share.
- Zero upside from SMRs.
- An 80% conversion rate of the reactors Westinghouse builds into subsequent O&M contracts.
- Upside from what we see as a new nuclear dawn in South Asia, which is not in Cameco’s table. We estimate the addressable South Asian new-build market at up to 90 GW by 2040. We assume a 50% probability this materialises and a 20% market share for Westinghouse.
What a USD 50bn+ valuation implies
We can also run our model in reverse, to see what set of assumptions a USD 50bn valuation would require. On our numbers, getting there implies two things relative to our base case. First, an 85% probability that the full US build goes ahead with Westinghouse winning all of it, against the 60% we assumed in our base case. Second, that the 66 GW of other large design contracts have a 40% probability of proceeding, with Westinghouse taking a 40% share, against the 25% probability we used in the base case. In other words, a USD 50bn valuation is not a stretch scenario on our framework. It is our base case with the US and international build probabilities moved up, though still well short of our bull case.
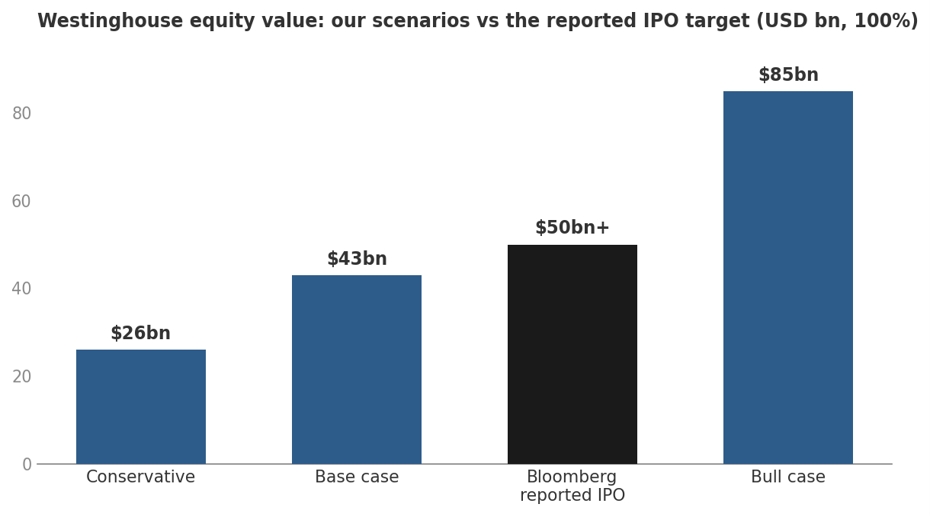
Source: Asymmetric Research; Bloomberg (reported IPO target). DCF-backed, 7.5% WACC.
How to play this?
A USD 50bn valuation changes the setup, and not in the obvious way. We ran the numbers against the uranium equity coverage applying our models. Where we would put money to work, and where we would not, is in the full note at Asymmetric Research.
[...]
Asymmetric Research is independent natural resources research. On 3 August we published a Westinghouse base case of more than USD 40bn; the reported IPO valuation is now over USD 50bn.
What sits behind the paywall: our full financial models and valuation tables, daily actionable commentary on the stocks we cover, and the positions we actually hold, including what we would buy and avoid on the back of this.
Read our work at asymmetricresearch.substack.com
***
Disclaimer: This note is for informational purposes only and does not constitute investment advice or a personal recommendation. Past performance is not indicative of future results. The value of investments can go down as well as up. Nuclear, uranium and related equities are highly volatile. Readers should seek independent professional financial advice before making any investment decision. Asymmetric Research may hold positions in uranium and related equities.