


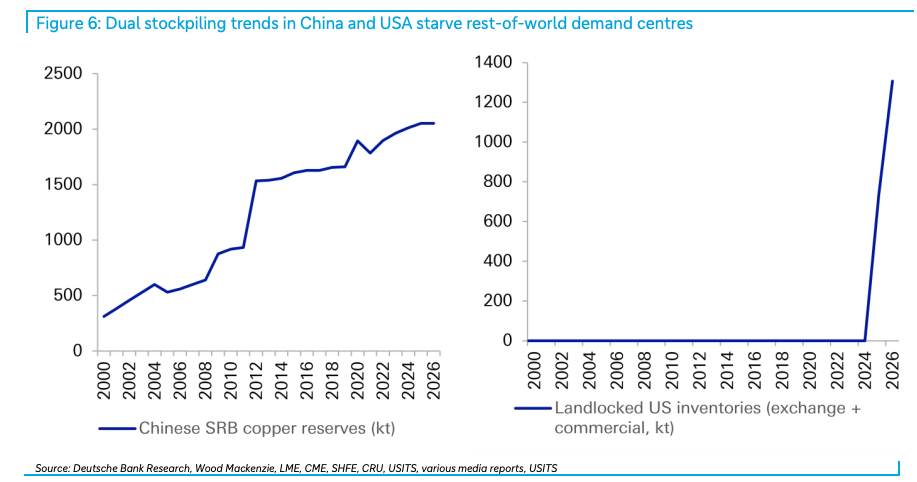
He starts by observing China holds an estimated 2.05 million tonnes in strategic reserves and US warehouse stocks heading toward 1.3 million tonnes by year-end. Industrial buyers elsewhere must now compete for the copper remaining outside those holdings.
He forecasts $22,050 per tonne in the second quarter of 2027, roughly 50% above prices when he issued this week’s analysis. He calls available inventories “unprecedented lows” and estimates that US and Chinese stockpiling will encumber 71% of global inventories by year-end.
China’s Reserves and US Warehouses
“The combination of de-globalization and decades of underinvestment in supply has created vulnerabilities such that, by year-end, stockpiling in the USA and China will have encumbered 71% of global inventories.”
The End-2028 Inventory Projection
ZH also noted:
Ghali called this the “most acute copper scarcity on record“ and a “de-globalization endgame.” The industrial metal’s story is quickly shifting from an AI data center boom to a liquidity crisis, as free-floating copper inventories decline to unprecedented levels.
The bank’s charts show Chinese copper concentrate treatment charges below zero and project refined-market deficits in 2027 and 2028. Smelters are competing for mine feedstock while stockpiling absorbs refined metal.