


A Rare Dislocation Opened in Uranium
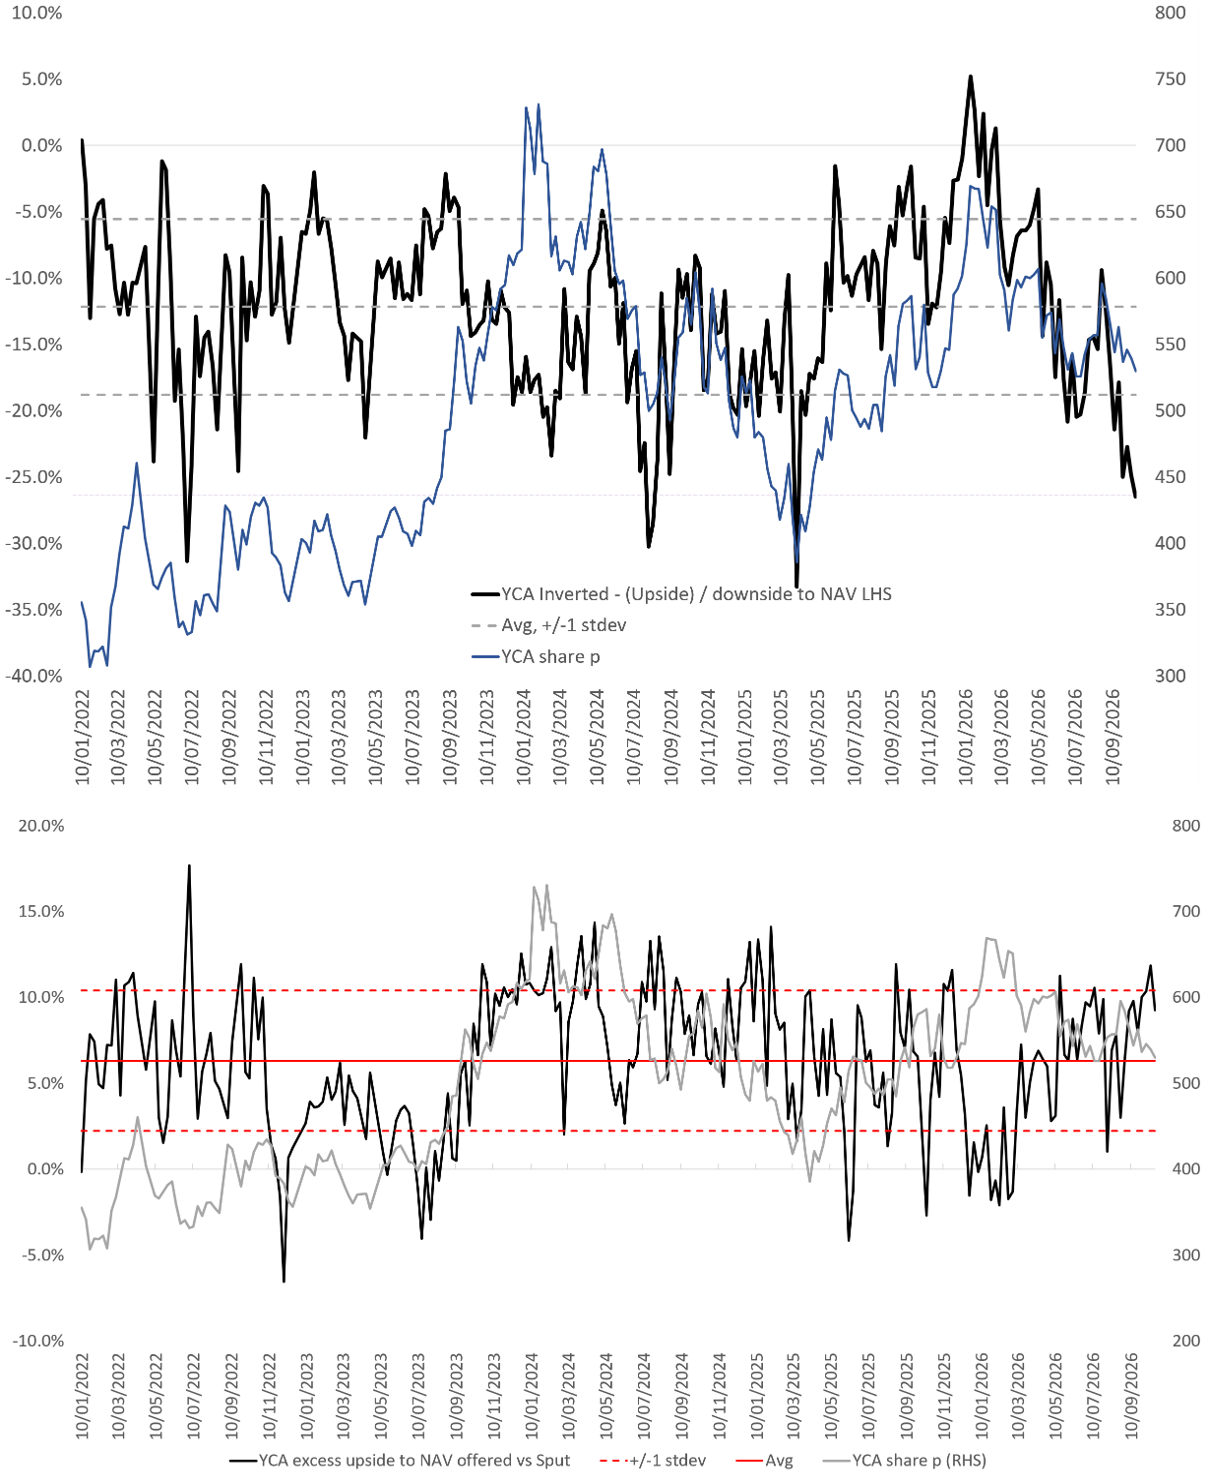
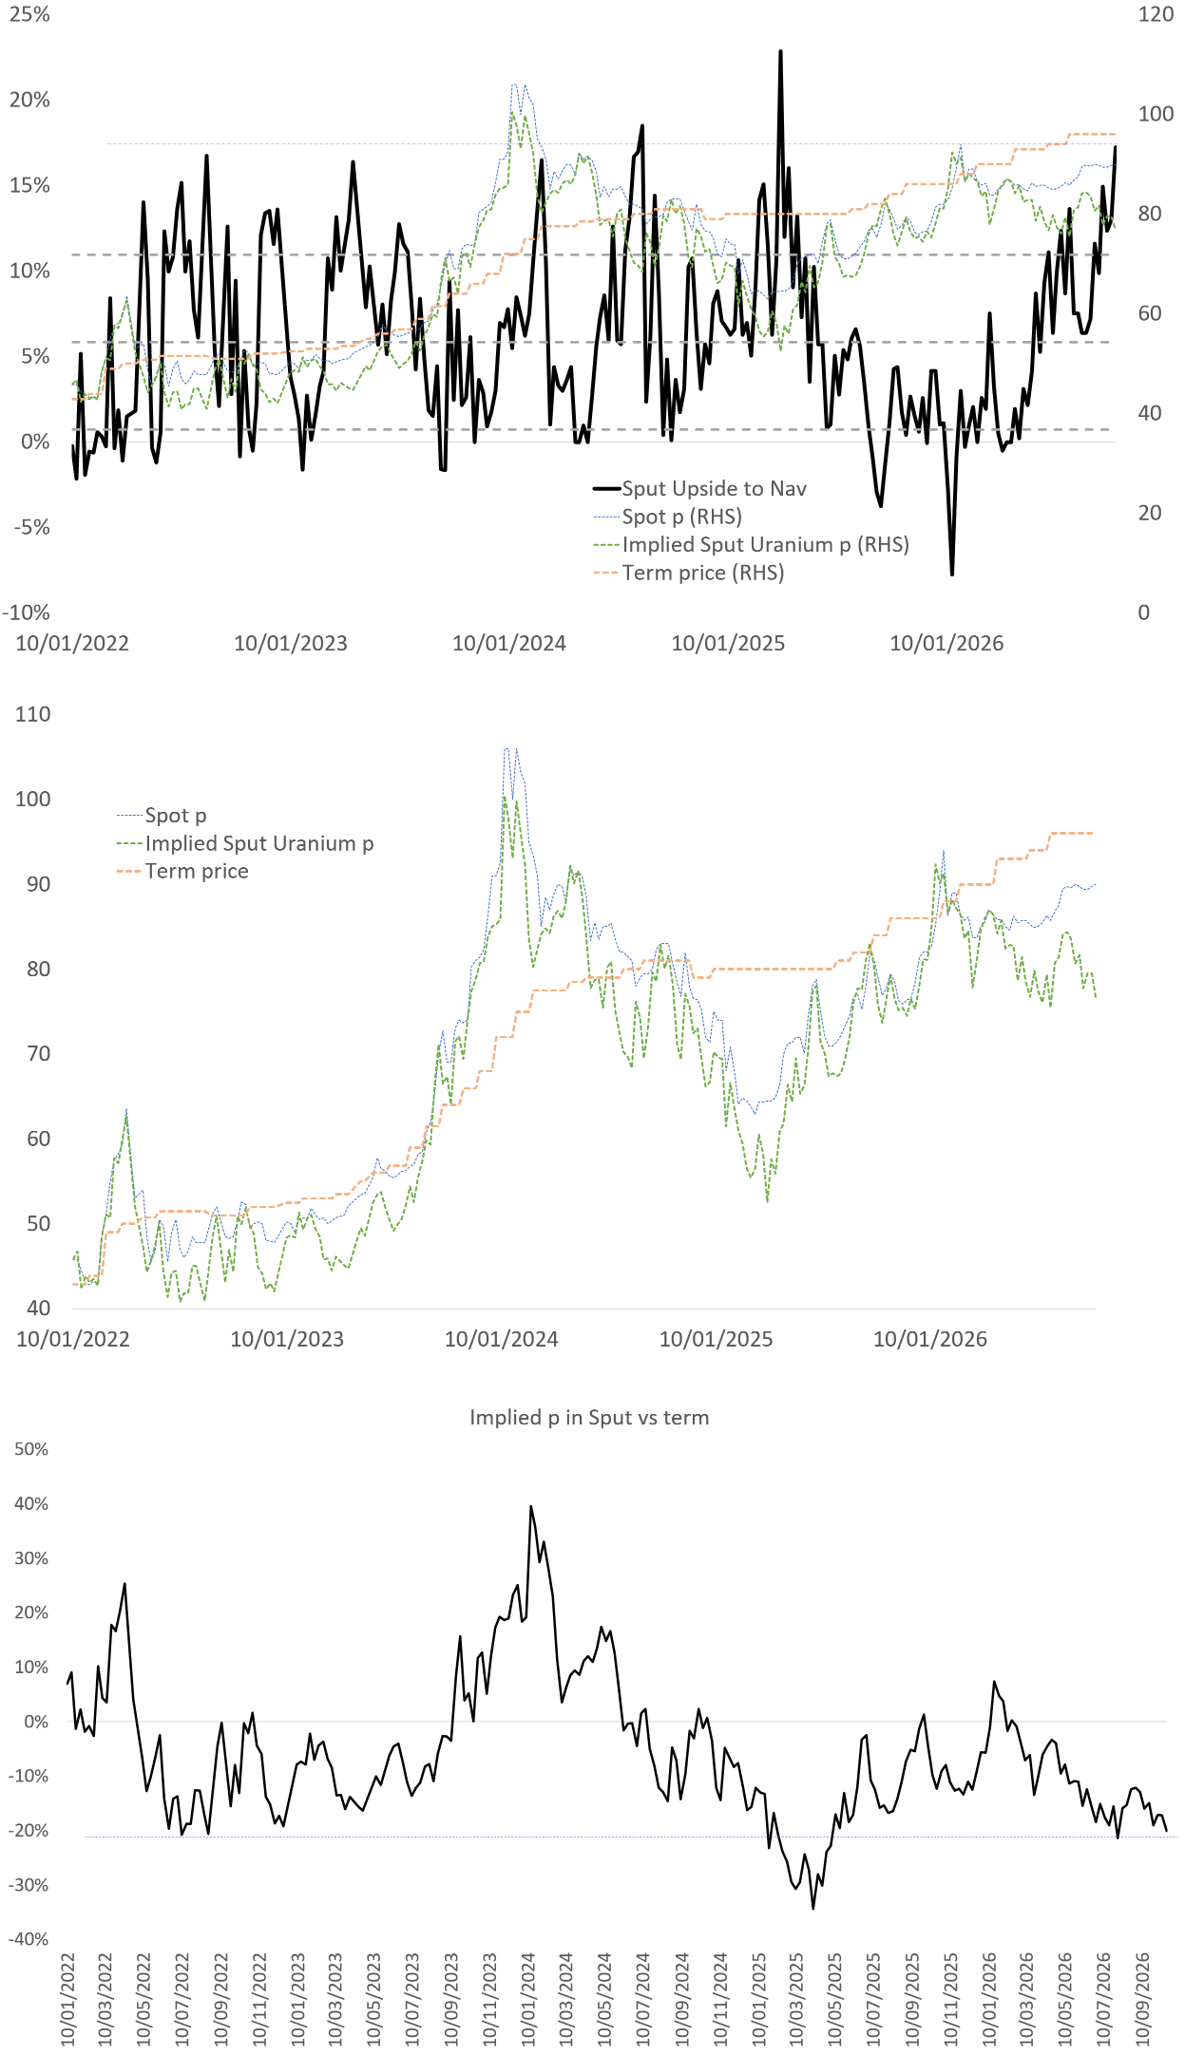
The key listed uranium physical funds, Sprott Physical Uranium Trust (SPUT, Canada and US listed) and Yellow Cake Plc (YCA, UK listed), are trading 2 standard deviations cheap versus history in terms of their discount to NAV. YCA furthermore trades near one standard deviation cheap to SPUT on this same relative metric.
These are extreme valuation disconnects, seen only twice since 2022 for SPUT and three times for YCA. Buying these instruments at those levels has historically generated a 15 to 20% return over the two following months, as the oversold NAV gap reverts to more normal levels. We think this time will be no different.
YCA's own relative NAV valuation historically, and relative NAV valuation to SPUT
Source: Asymmetric Research, company reports. *YCA and SPUT implied prices factoring in fund operating costs
SPUT relative NAV valuation historically, and its implied uranium price versus spot and term prices (%, $/lb)
Source: Asymmetric Research, company reports, Numerco, UxC
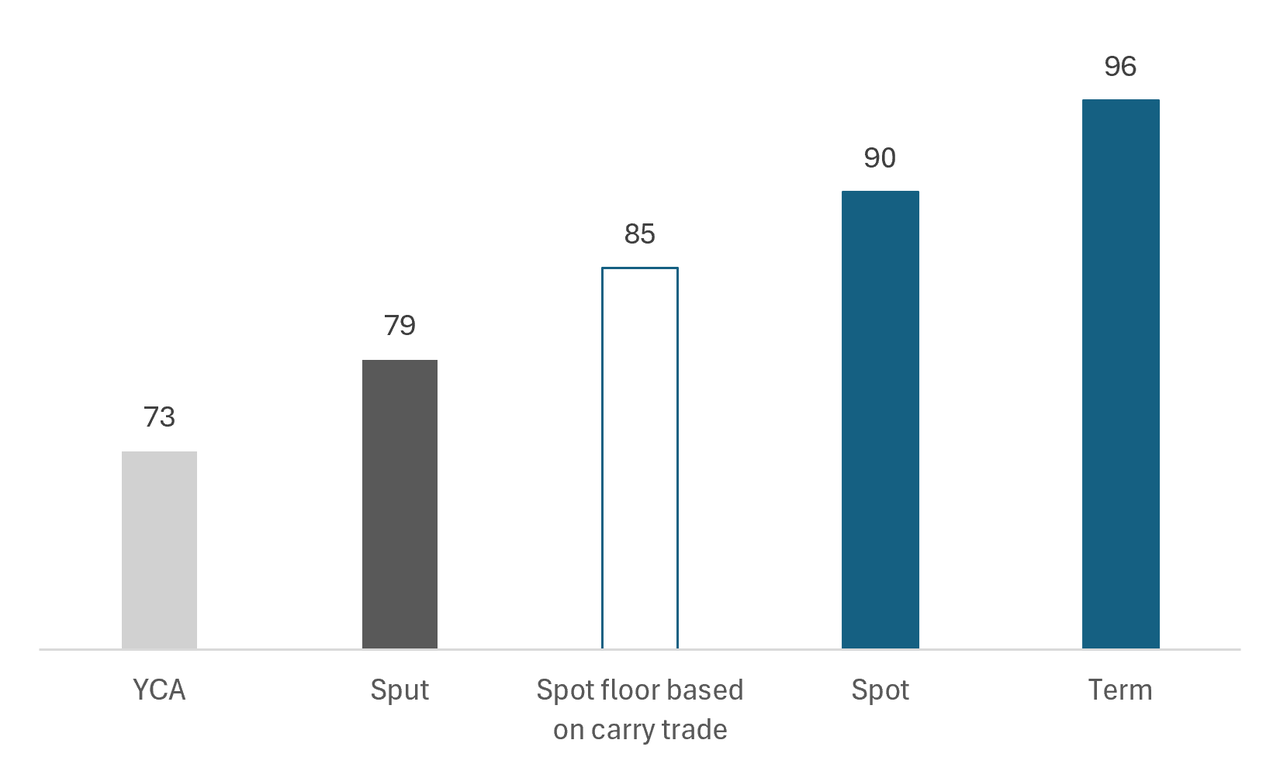
By buying into the physical funds here, one is buying uranium around $14/lb cheaper than spot, and around $20/lb cheaper than term, on average across both vehicles.
Implied uranium prices in the key listed physical funds vs spot, term, and our estimate of the spot floor based on the carry trade ($/lb)
Source: Asymmetric Research, company data, UxC. *Our estimates of YCA and SPUT implied prices factoring in fund operating costs
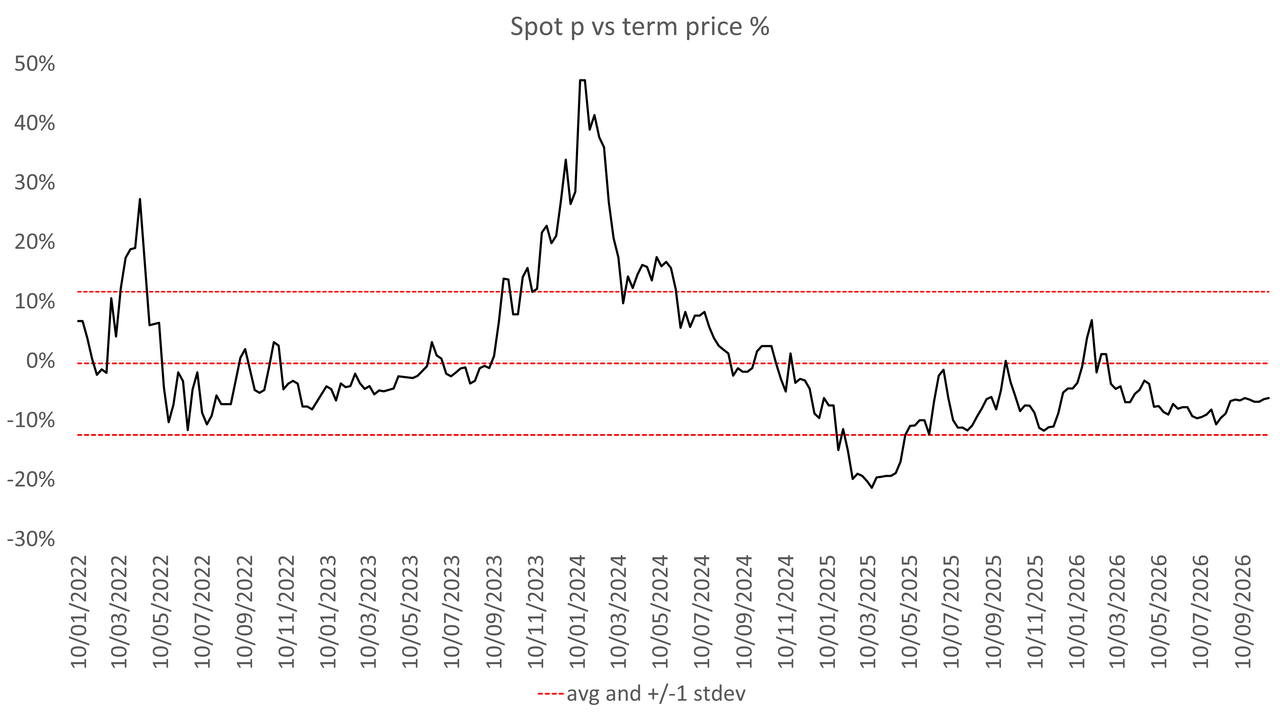
One evidently needs confidence that uranium prices hold up. We would note that historically the uranium spot price has traded in line with the term price, whereas it is currently at around a 6% discount, meaning spot is arguably conservatively priced.
Uranium spot vs term prices ($/lb)
Source: Asymmetric Research, Numerco, UxC
Furthermore, we estimate that carry trades would be possible with a spot price at $85/lb and below, putting a floor under spot. SPUT and YCA are here priced at a $6 to $12/lb discount respectively to that floor.
The question is therefore whether the term price holds up. We think so. The steadily rising term price this year reflects genuinely improving supply and demand, and the uranium case remains a two-year story to reap the rewards. We see the Iran crisis as a structural shift in the nuclear bull case, and expect it to accelerate new build. A comparable shock in the 1970s produced a 6x move in uranium prices between 1973 and 1976, as we set out in our recent reports.
On supply and demand, even stripping out everything speculative, that is, excluding (1) a full new nuclear build cycle, (2) data-centre demand, (3) SMR upside, and (4) any utility contracting above replacement rate, our current conservative model only balances around 2031, once NexGen's Arrow comes online. The setup does not require the blue-sky to work.
———
Asymmetric Research reached #16 Rising in Finance on Substack in October 2026. Subscribe to Asymmetric Research, and upgrade for the full research: model-driven fair values and sensitivities across the 40-plus stocks we cover in uranium, gold, gas and critical minerals, actionable daily commentary, our positioning, and direct access, we reply.
asymmetricresearch.substack.com
***
Disclaimer: This note is for informational purposes only and does not constitute investment advice or a personal recommendation. Past performance is not indicative of future results. The value of investments can go down as well as up. Uranium and related equities are highly volatile. Readers should seek independent professional financial advice before making any investment decision. The author holds positions in uranium and related equities, including YCA.