





Sometimes, Knives Just Keep Falling
Submitted by QTR's Fringe Finance
There’s an old expression on Wall Street about trying to “catch a falling knife.” It refers to buying a stock that’s rapidly declining in price, hoping to pick it up at a bargain before it rebounds.
The obvious risk is you grab the knife before it hits the ground and wind up getting cut. But the expression also carries an implicit assumption that I think investors have become dangerously comfortable with: that eventually, the knife hits the ground (and the stock bounces).
For the better part of the last 15 years, investors have been conditioned to believe that virtually every meaningful decline in a stock is a buying opportunity. We have achieved full mass delusion psychosis as far as equity market participants are concerned.
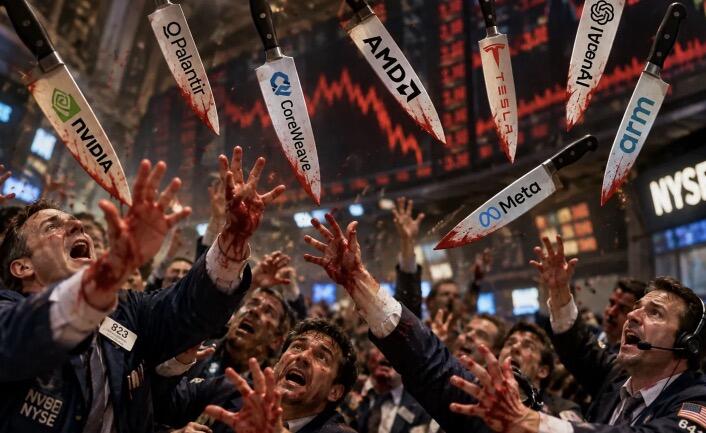
Stocks go down, investors pile in, stocks go back up, and everybody congratulates themselves for being geniuses. Rinse, repeat, collect your winnings, and wait for the next opportunity to do it all over again. It happens with individual names, and it happens with indexes…over and over. Dip buyers are crowned as geniuses even if they are buying total dogshit, skeptics are made to look like imbeciles. This record has been playing for decades.
To the bulls, fine. I give up. In the words of Dennis Green:
“If you want to crown them, then crown their ass!”
But there’s a fairly important distinction that seems to have gotten lost somewhere along the way that is very important everyone understands: not every stock has a fundamental floor beneath it. While most knives bounce, all of them don’t. And as the market gets more volatile, we’re going to see more knives that just don’t stop falling.
The assumption behind buying the dip is that, at some point, a company’s valuation becomes so attractive relative to its underlying business that investors will step in and support the share price. Maybe the earnings multiple gets too cheap. Maybe the company’s assets are worth more than its market capitalization. Maybe the cash flow yield becomes irresistible. Maybe there’s enough cash on the balance sheet to justify the entire valuation.
Those are legitimate fundamental arguments. And in many cases, they provide perfectly good reasons to buy stocks that have been beaten to a pulp.
But what happens when none of those things exist? What happens when...(READ THIS FULL ARTICLE 100% FREE HERE).