Hedge Funds Capitulate, Credit Still Screams... Why Won't Nasdaq Break?
The great disconnect
Markets are bouncing, but the damage beneath the surface is hard to ignore. Record tech selling, collapsing hedge fund exposure, widening credit spreads and mounting sovereign stress are all flashing warning signals. Yet NDX remains trapped in its range, valuations have compressed sharply, and positioning has already been washed out. The tension between deteriorating fundamentals and increasingly extreme positioning is what makes this market so interesting right now.
Still stuck
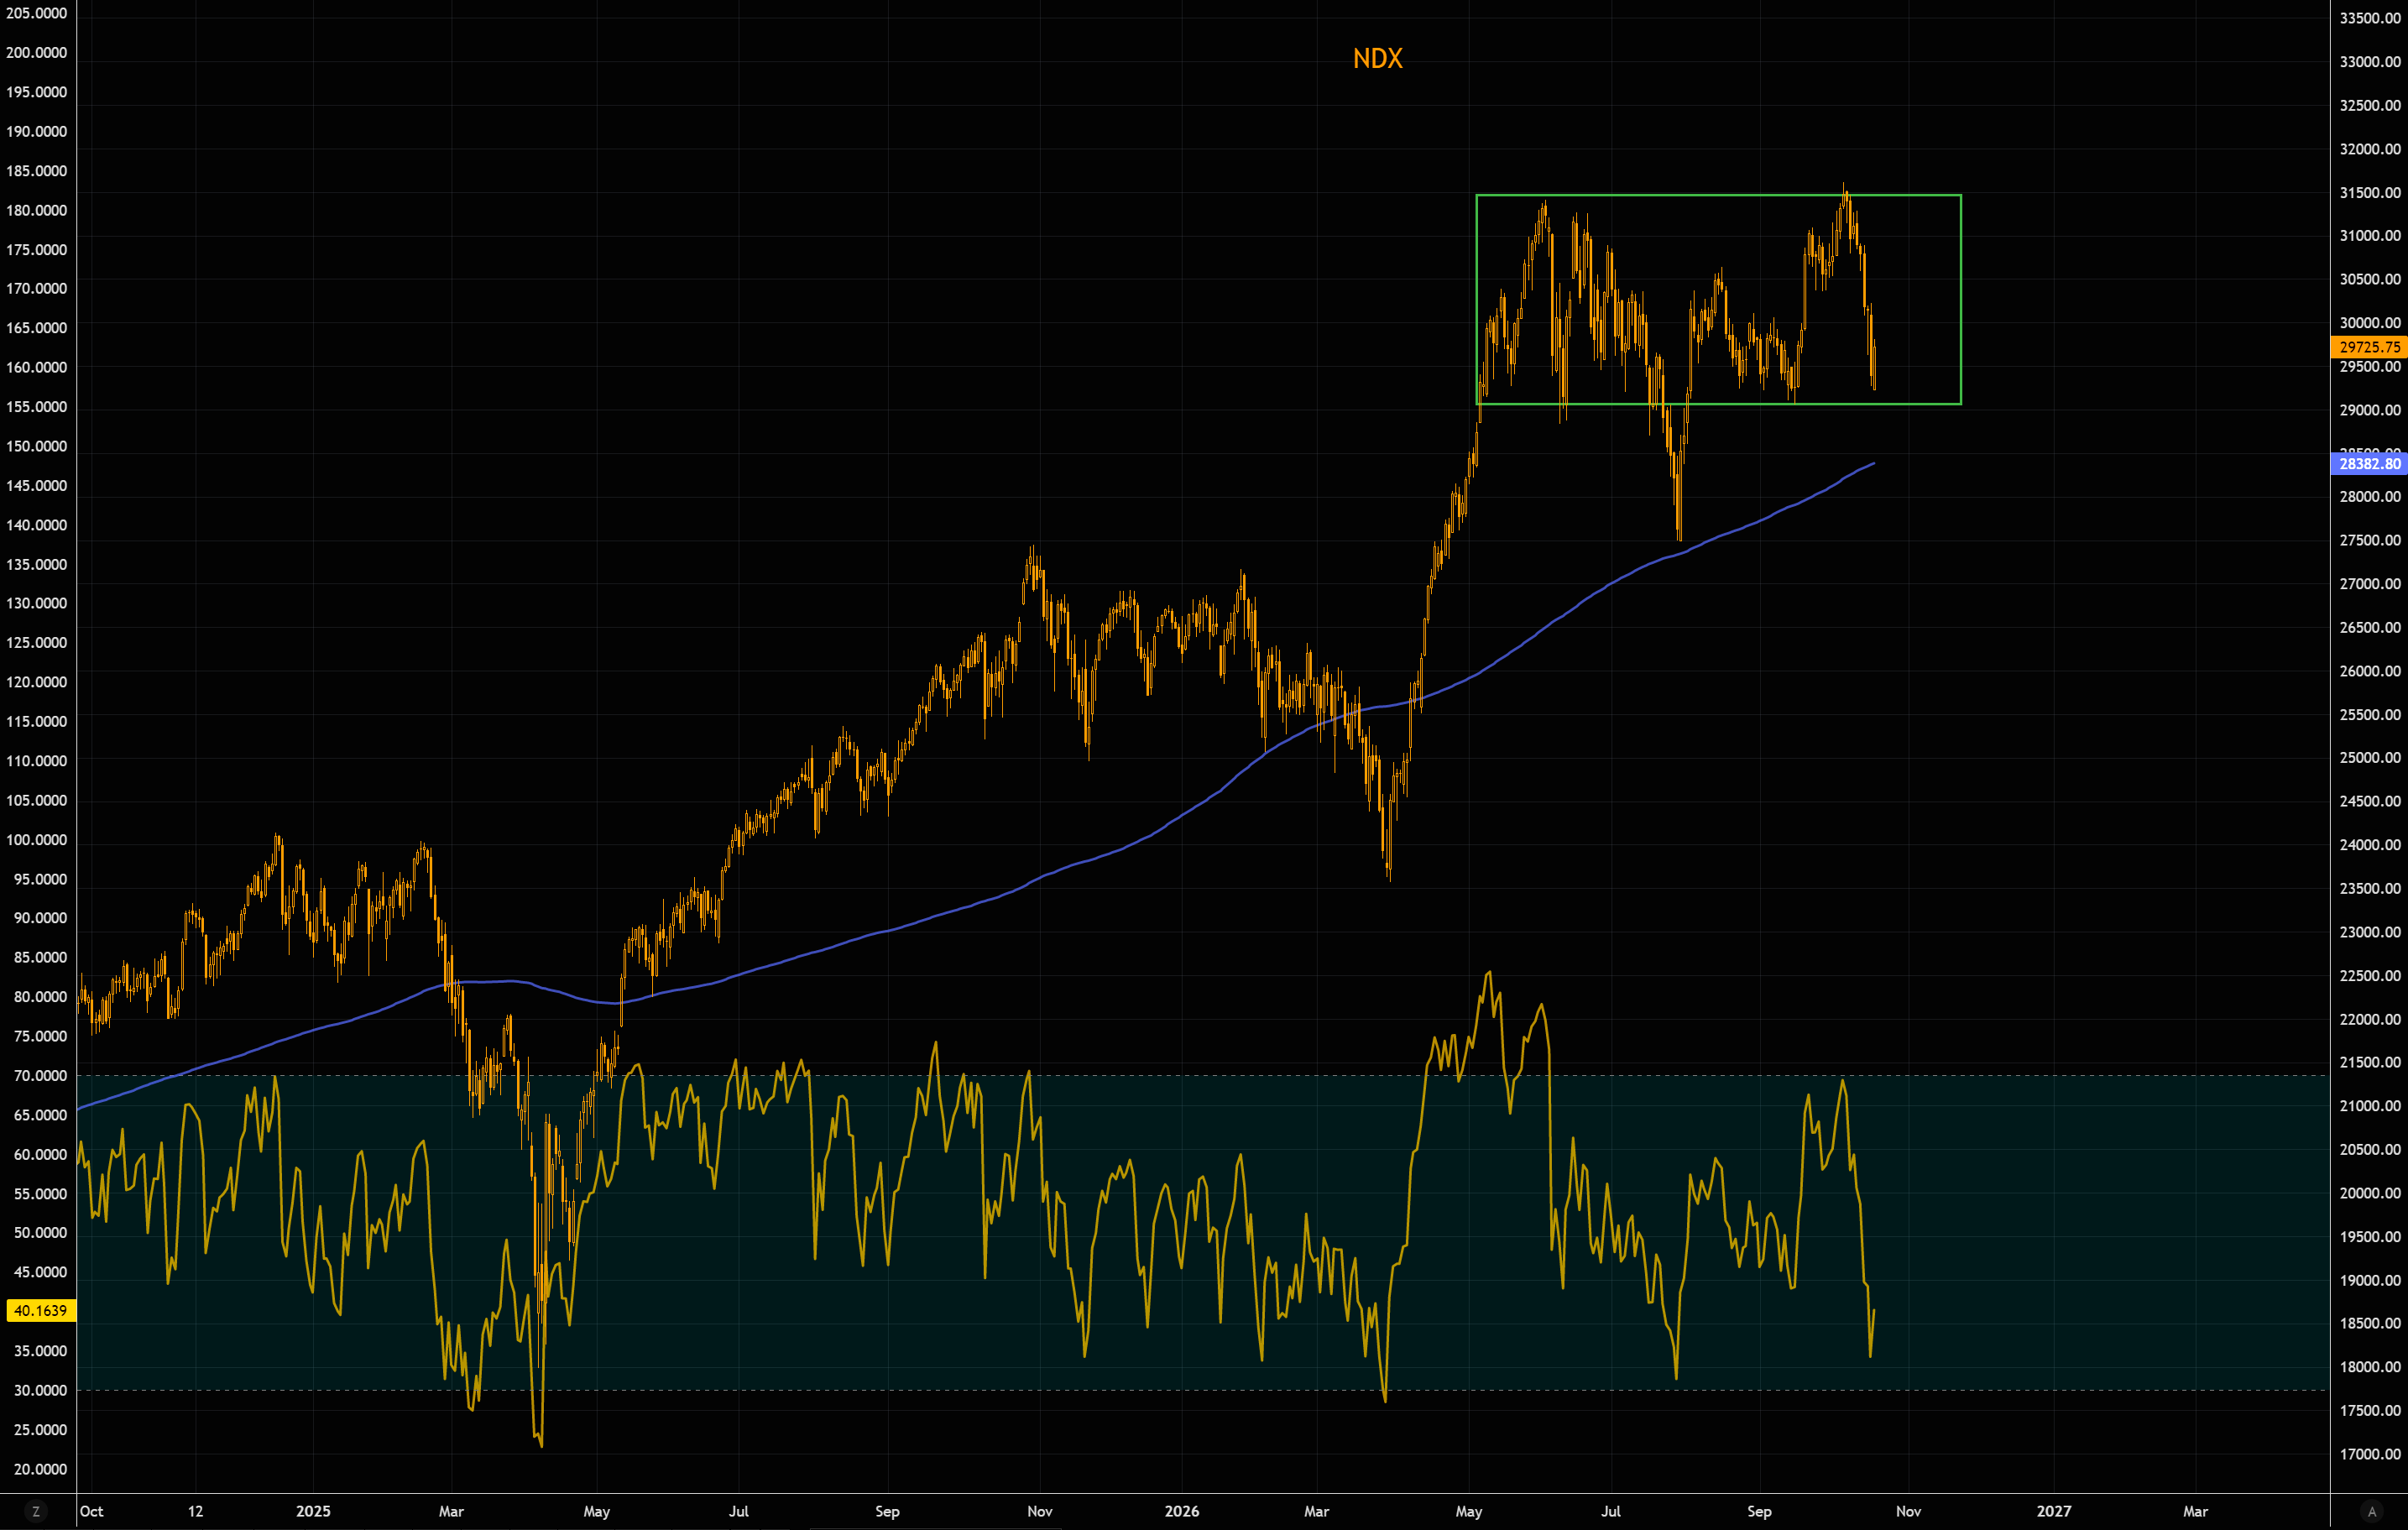
For all the violent moves beneath the surface, NDX has yet to break out of its trading range in either direction. Futures are bouncing from extremely oversold levels, while the 200-day moving average still sits lower. One thing worth remembering: chasing momentum breaks in either direction has been a costly strategy over the past six months. More here.
Source: LSEG Workspace
The tech puke
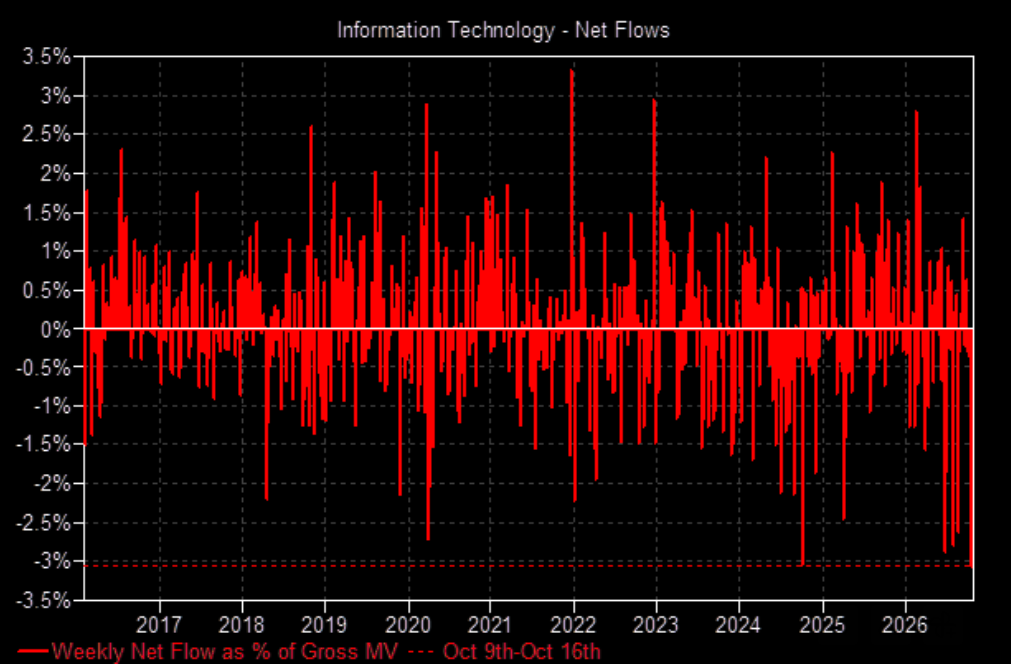
In case you missed it: Information Technology was the most net-sold sector, with net selling reaching the highest level on record.
Source: GS
0th percentile
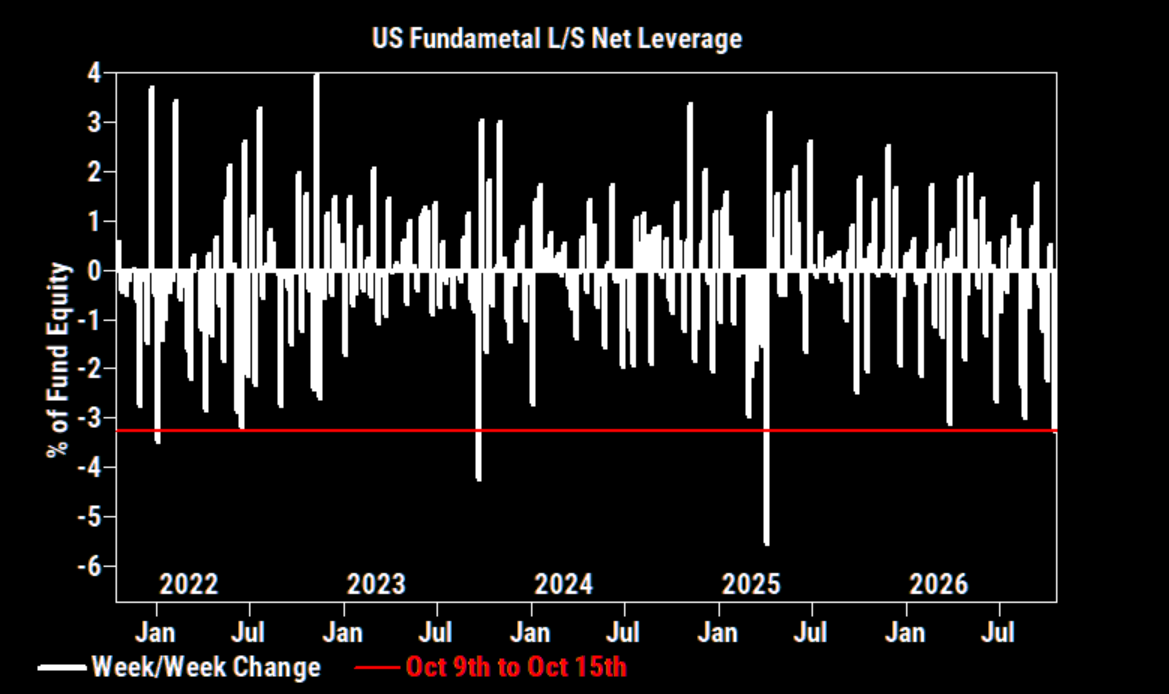
GS Prime: US Fundamental L/S Net leverage fell -3.2 pts – the largest weekly decline since Apr ’25 (week of Liberation Day) and the 4th largest weekly decline in the past five years – to 43.7% (0th percentile five-year).
Source: GS Prime
The great de-rating
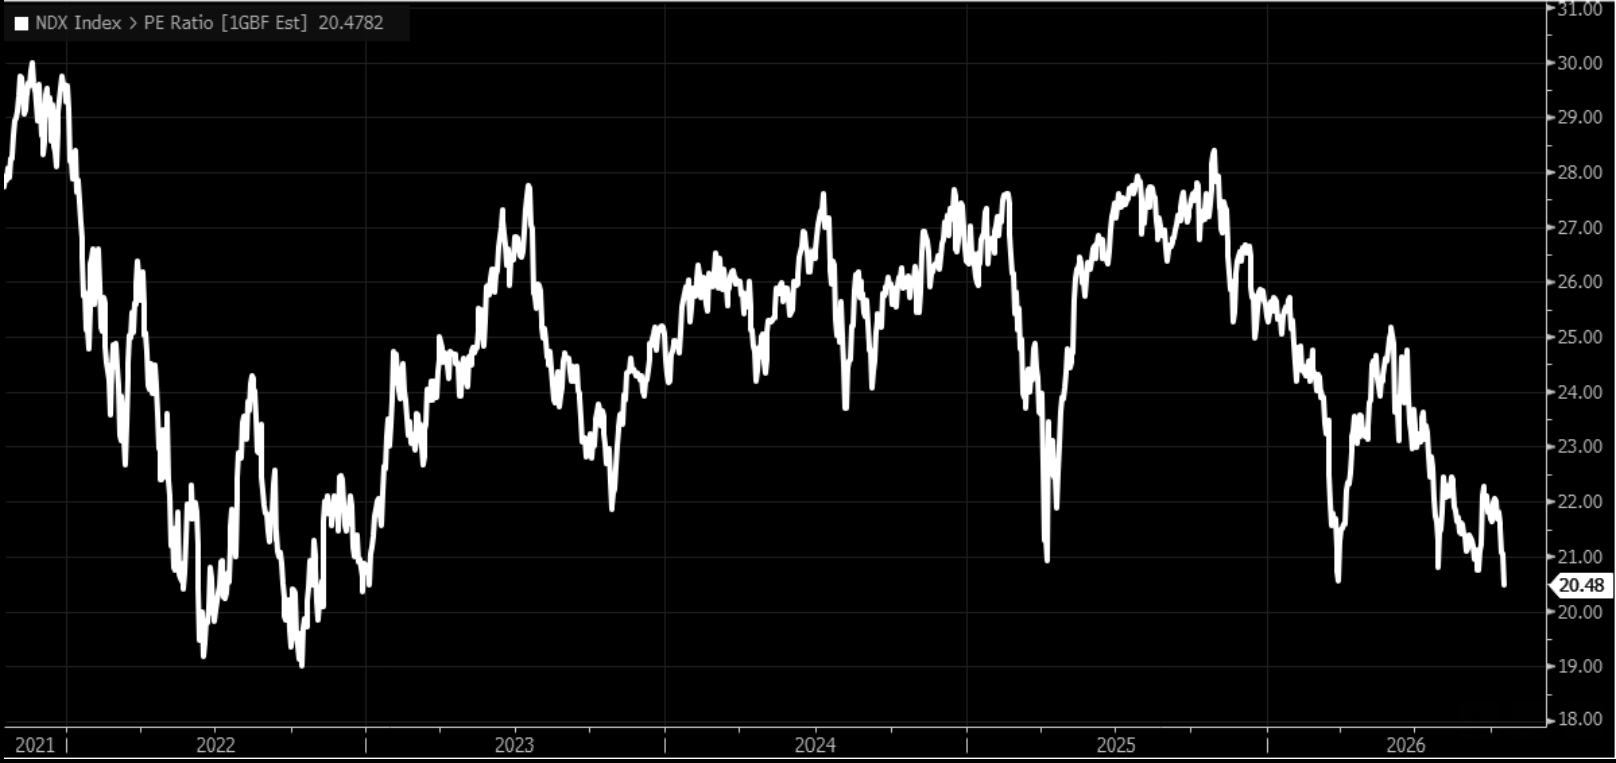
NDX forward P/E has compressed to 20.5x, its lowest level since the AI cycle began in 2023. The index now trades at just a 1.8x premium to the S&P 500, the narrowest in nearly a decade.
Semis have led the valuation collapse, with forward P/E plunging from around 29x this summer to just 17x today.
Source: GS
VIX call love
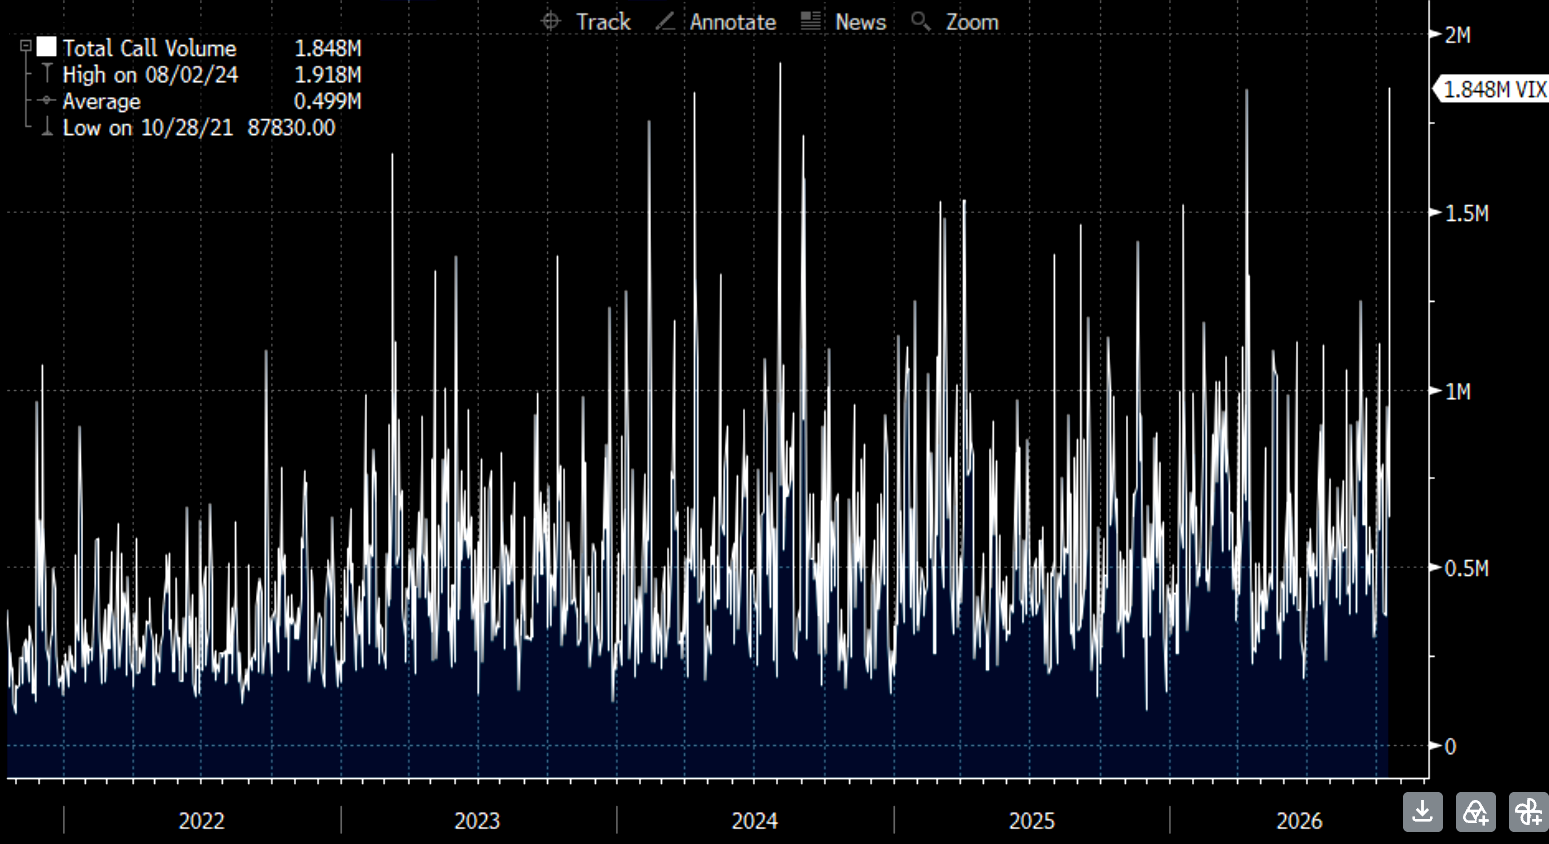
VIX call volume surged to its second-highest level in five years, surpassed only by August 2, 2024, just before VIX exploded above 60 the following Monday. Quite a shift in investor behavior. Latest note on vol here.
Source: GS/Bloomberg
The credit disconnect
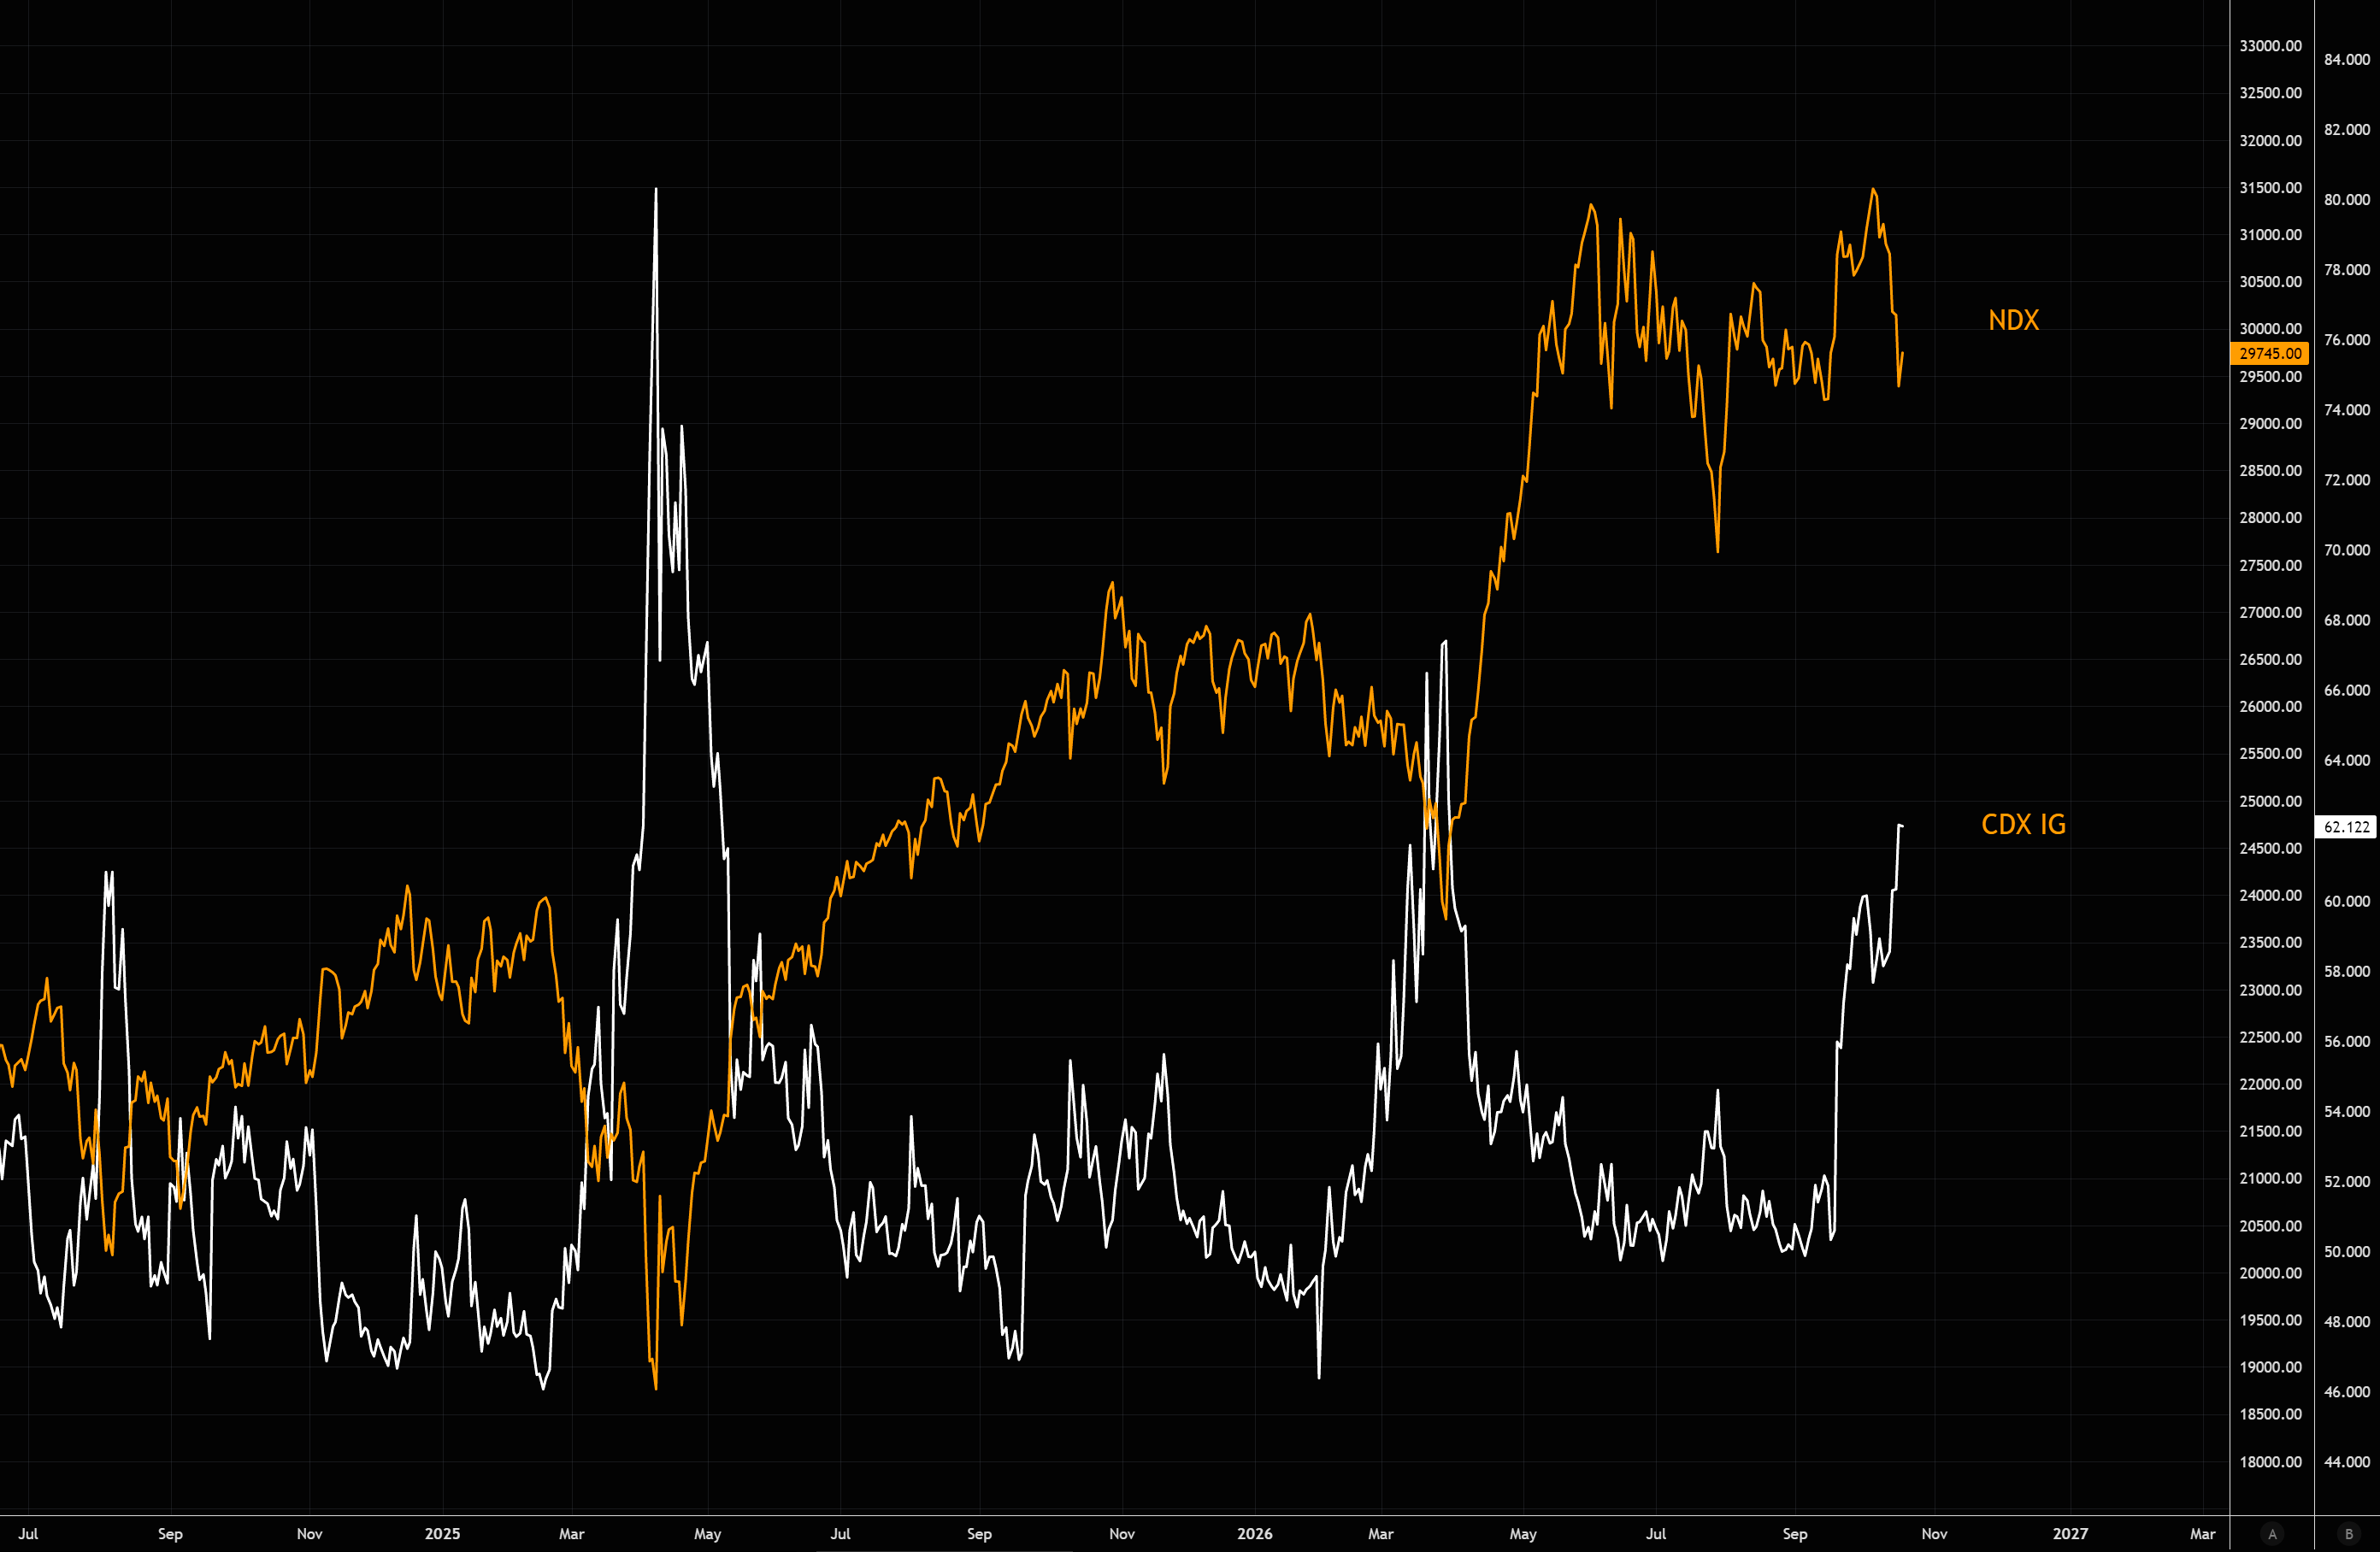
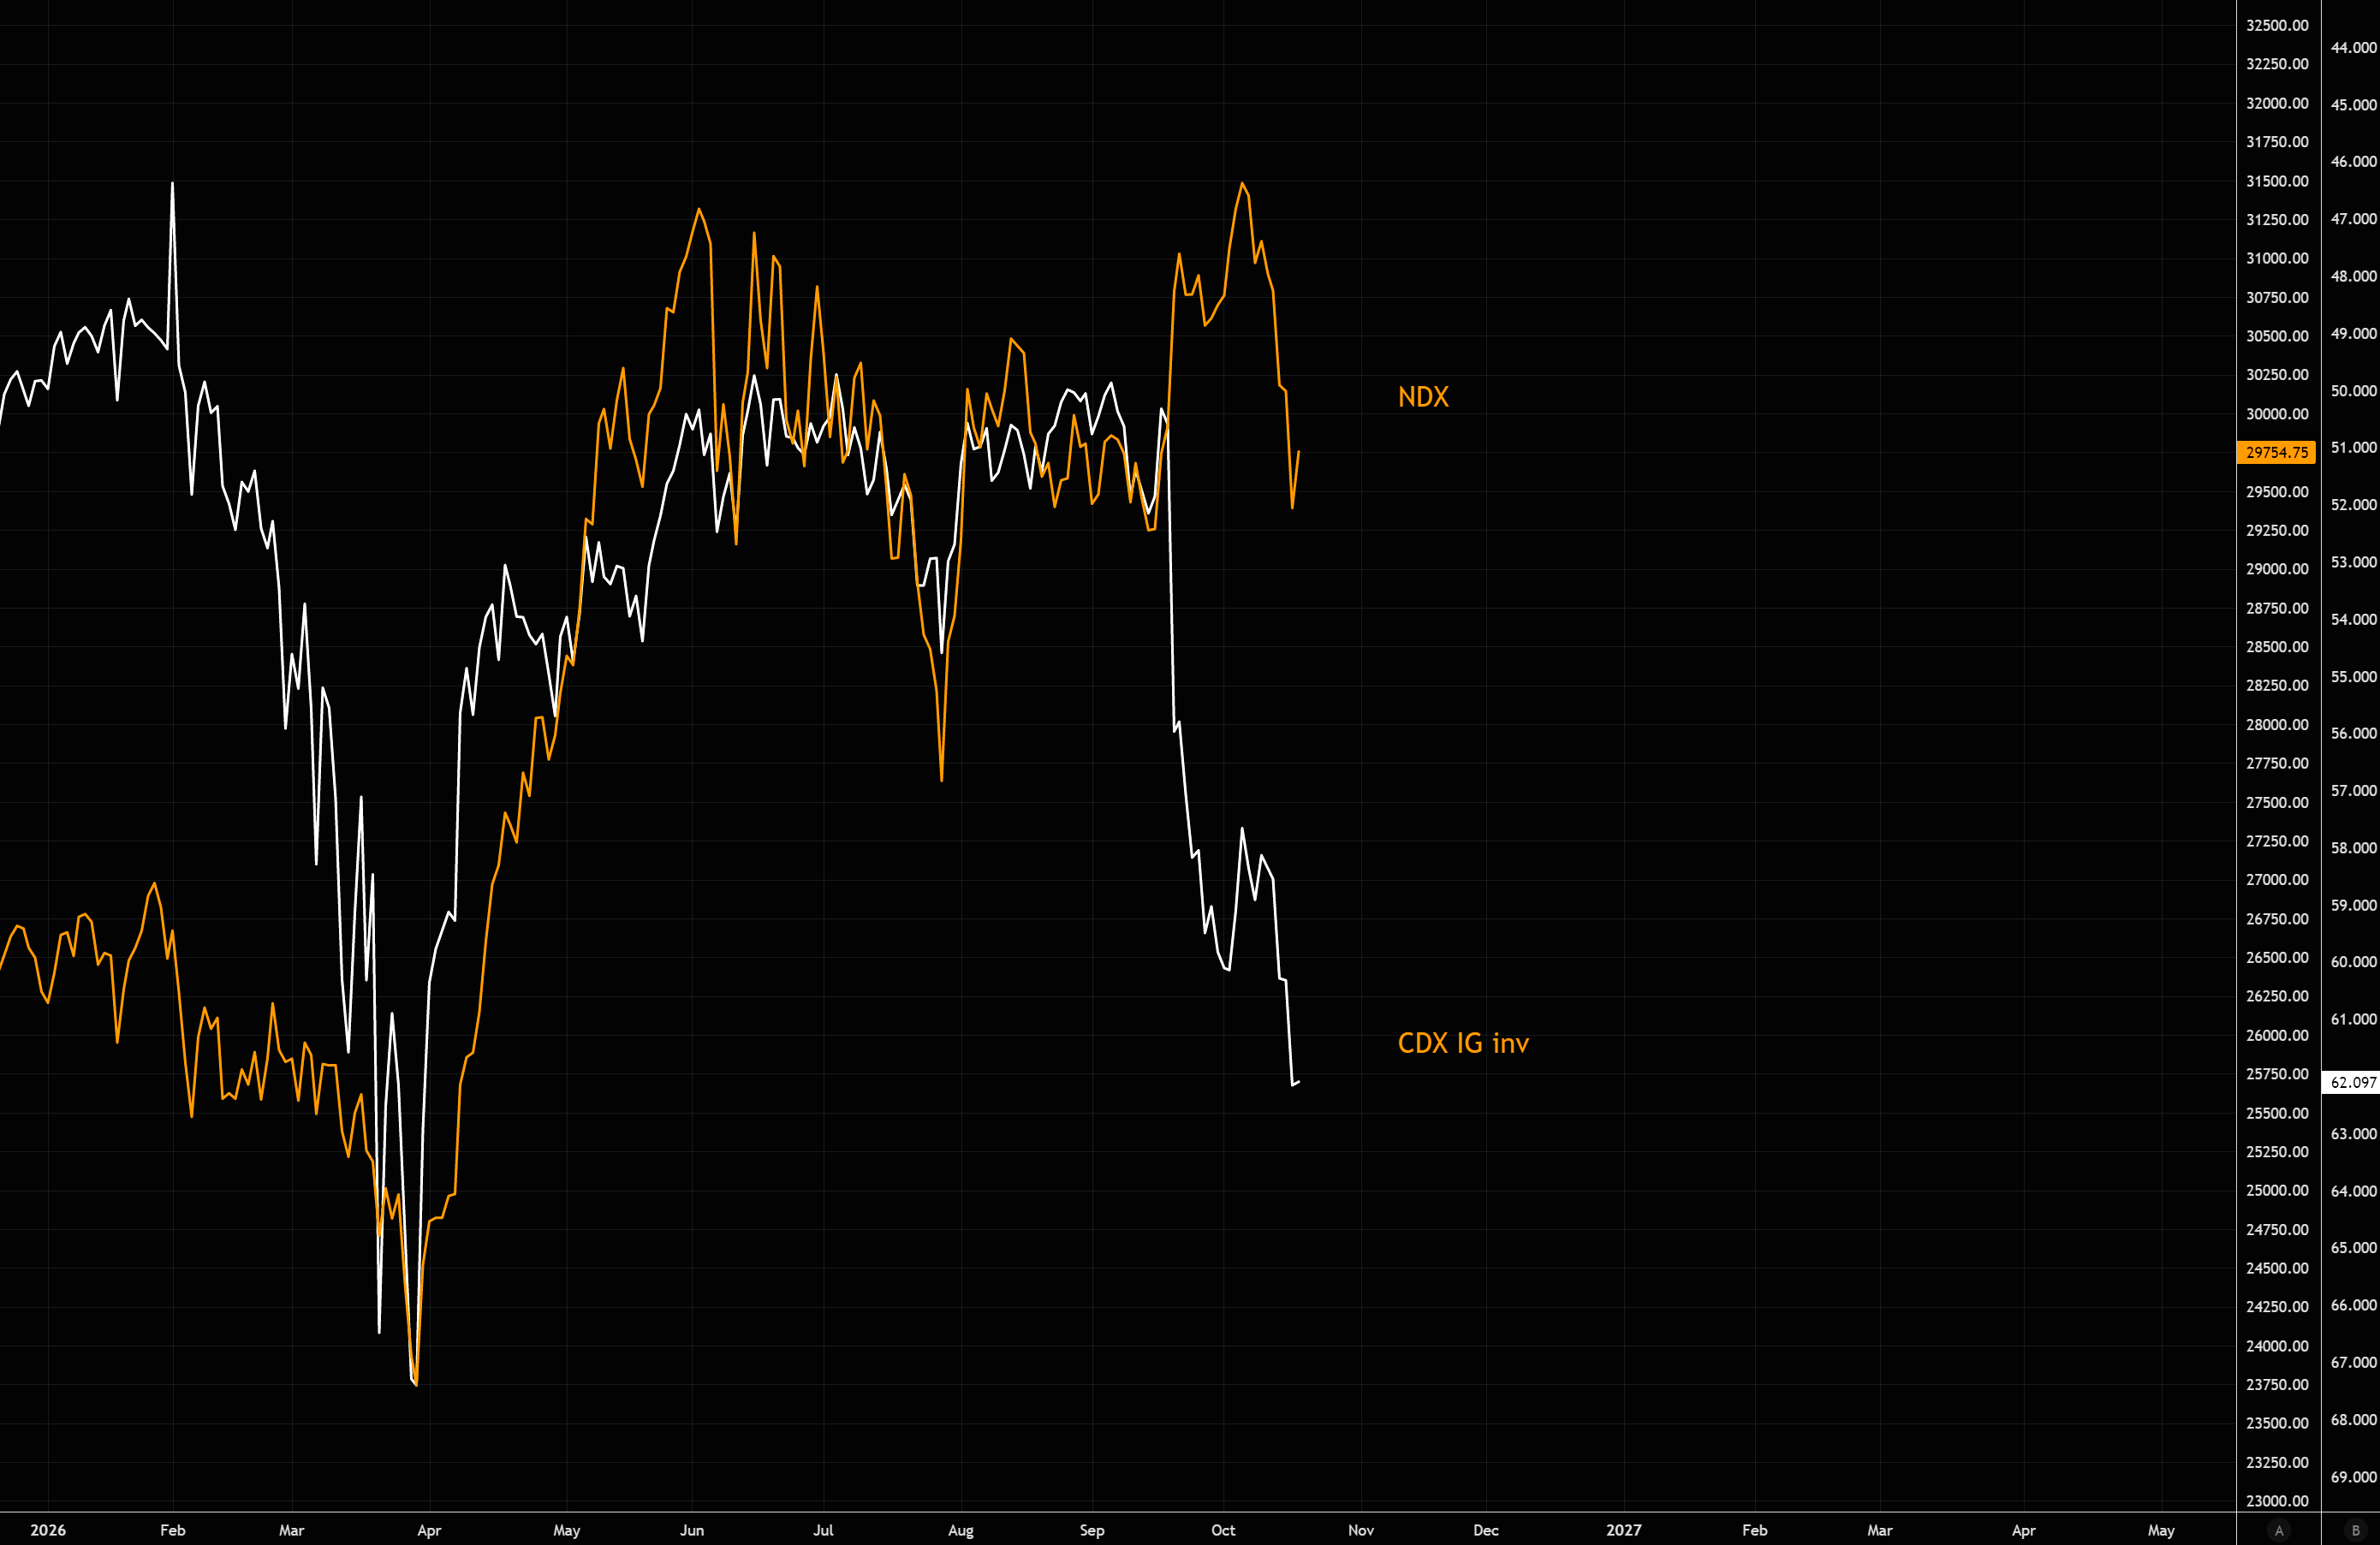
Persistent credit stress continues to haunt this market. Equities, particularly tech, have started to reflect some of the deterioration, but the divergence remains striking. NDX is back around mid-September levels, while CDX IG spreads have widened dramatically over the same period.
The second chart shows SPX versus inverted CDX IG, offering a clearer perspective on the magnitude of the credit move. Comparing mean-reverting credit spreads with trending equity indices over longer periods has its limitations, but this divergence is not something to dismiss lightly.
Source: LSEG Workspace
Source: LSEG Workspace
Credit pressure persists
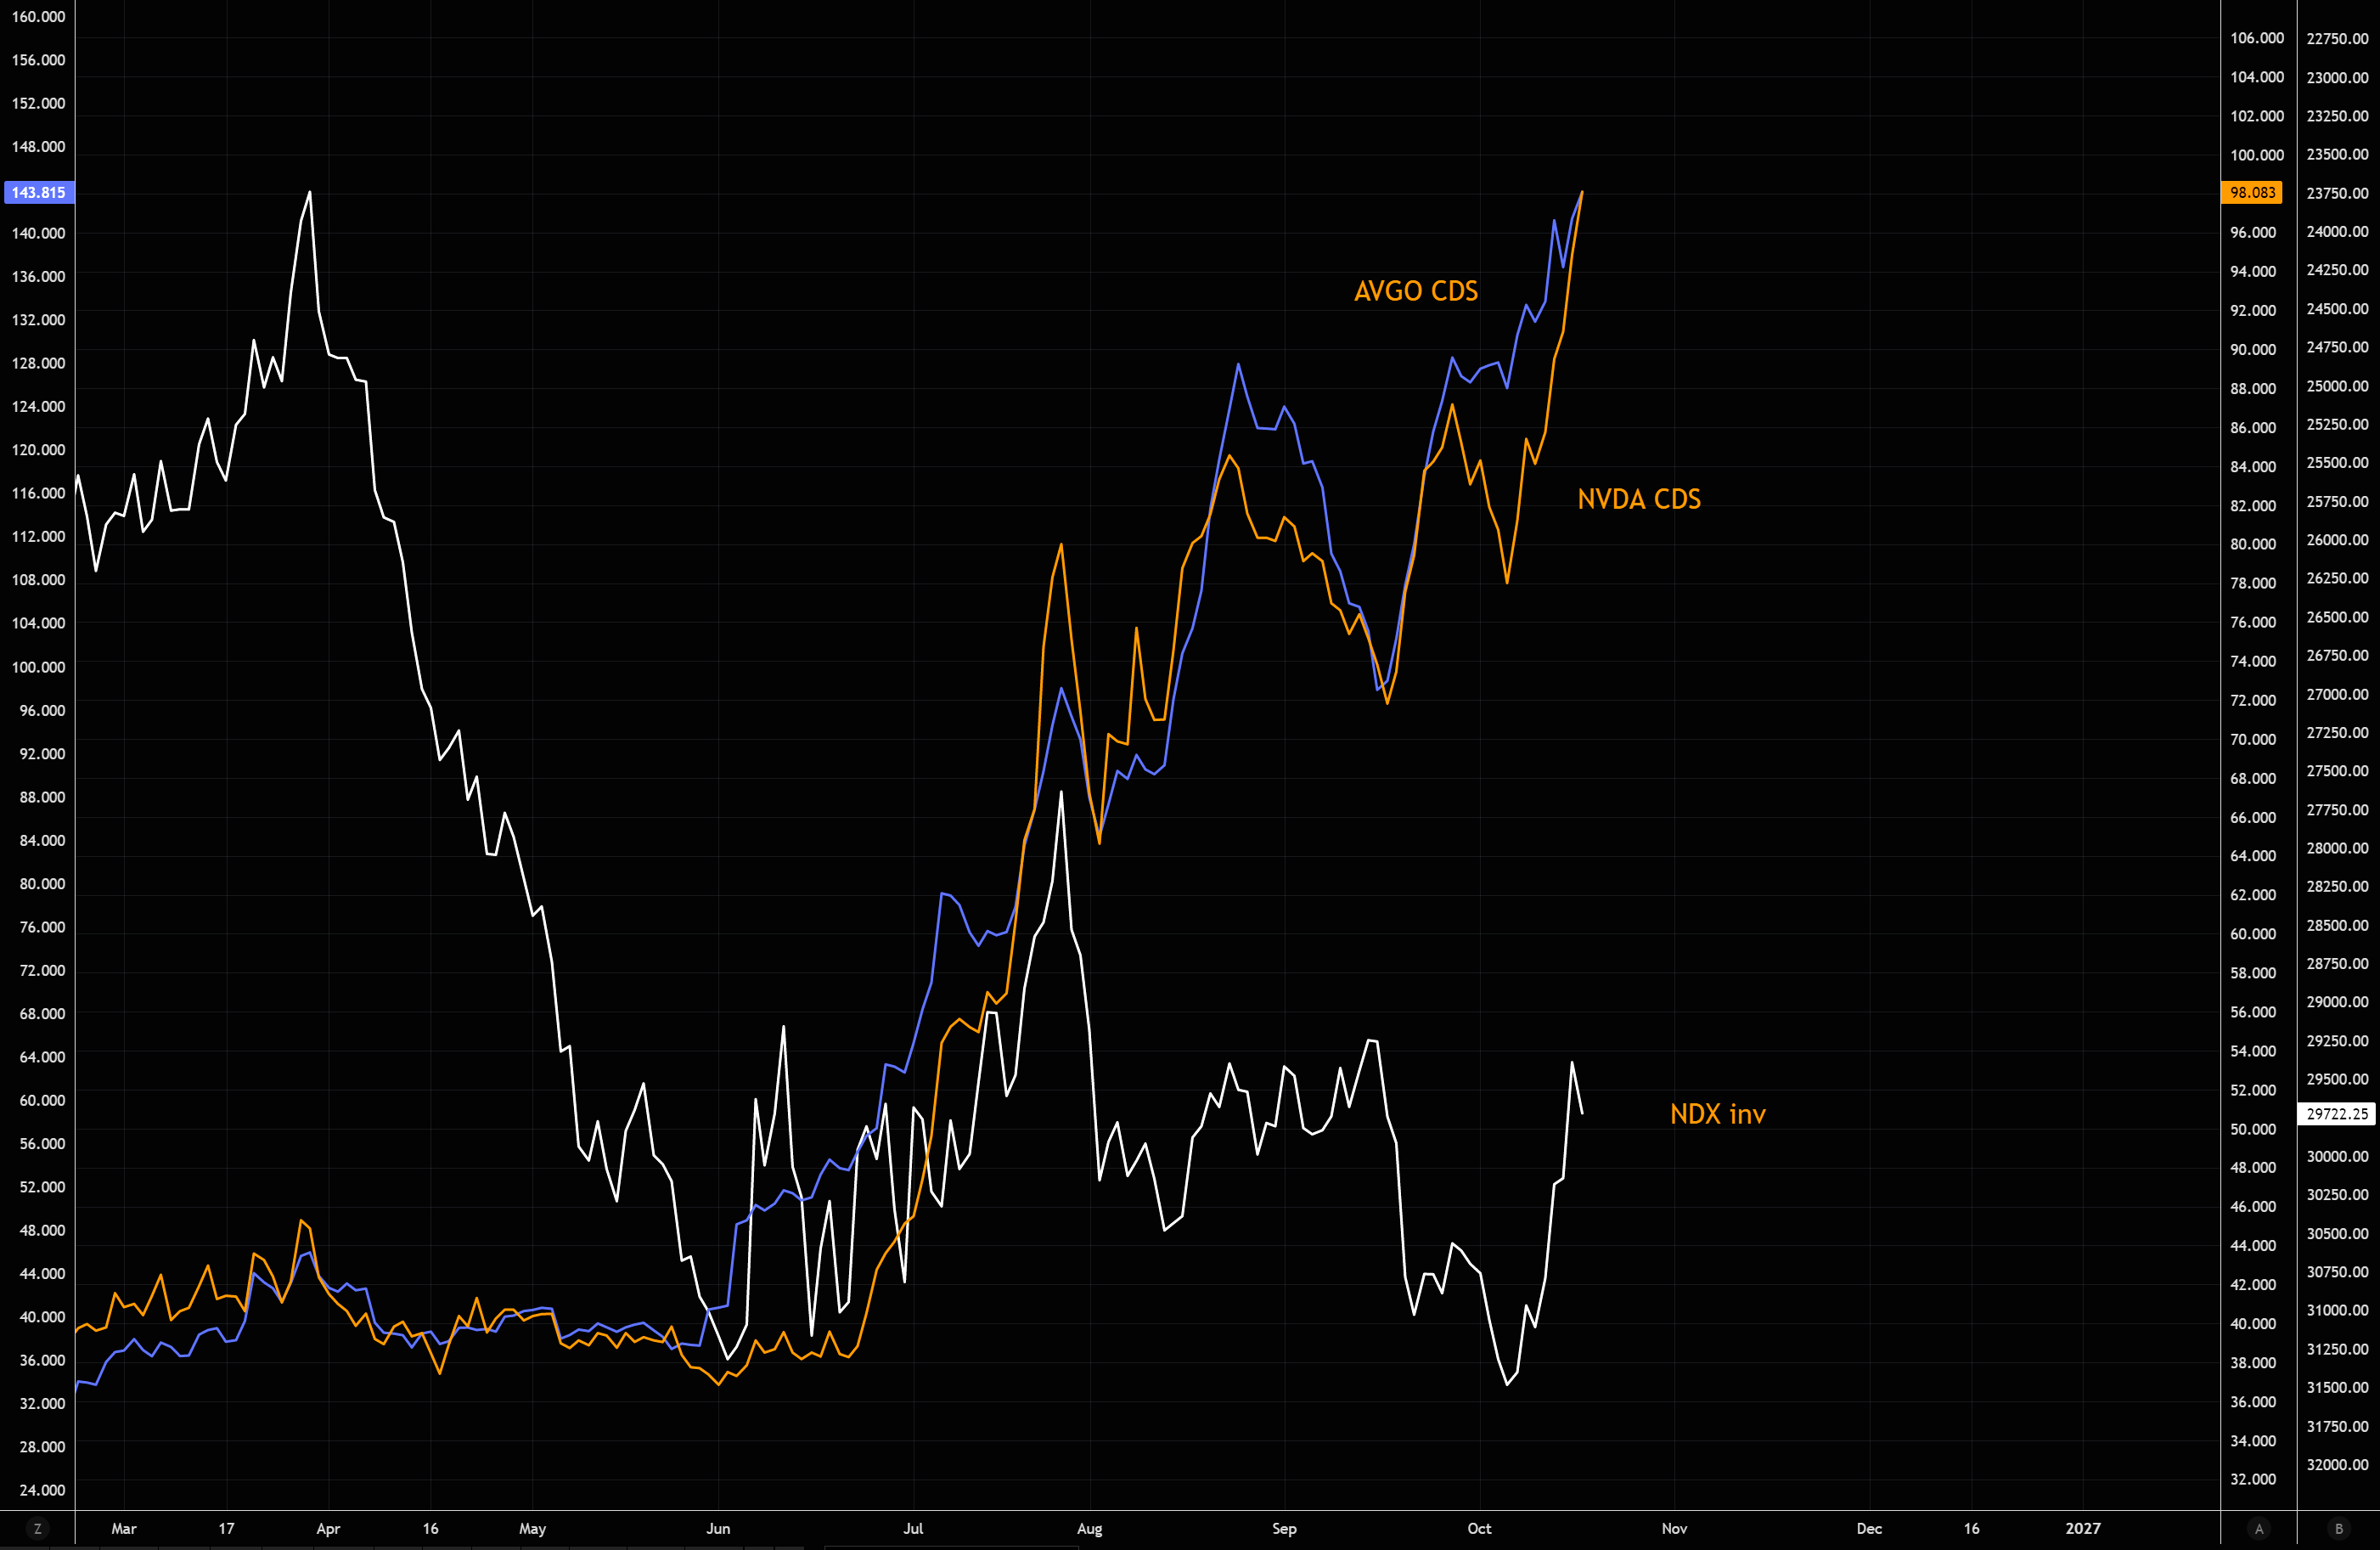
NVDA and AVGO CDS spreads continue to widen. NDX has largely followed the deterioration in credit markets, at least until today's bounce. Let's see how this plays out, but one thing is clear: the pressure from credit markets remains firmly intact. More here.
Source: LSEG Workspace
The recycling machine
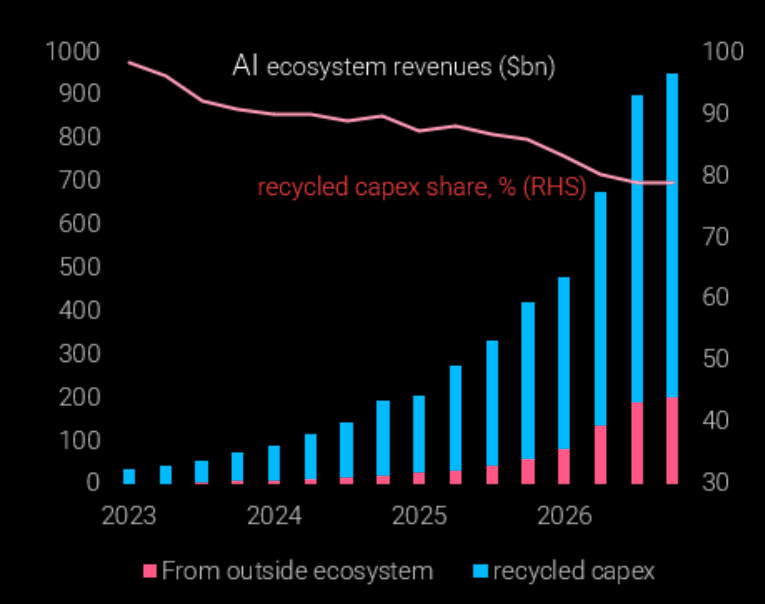
AI revenues are growing rapidly, but where is the money actually coming from? TS Lombard estimates that roughly 80% of AI ecosystem revenues are still tied to recycled capex rather than demand from outside the ecosystem. The critical question is when genuine end-user demand starts catching up with the investment boom. More here.
Source: TS Lombard
The new safe haven
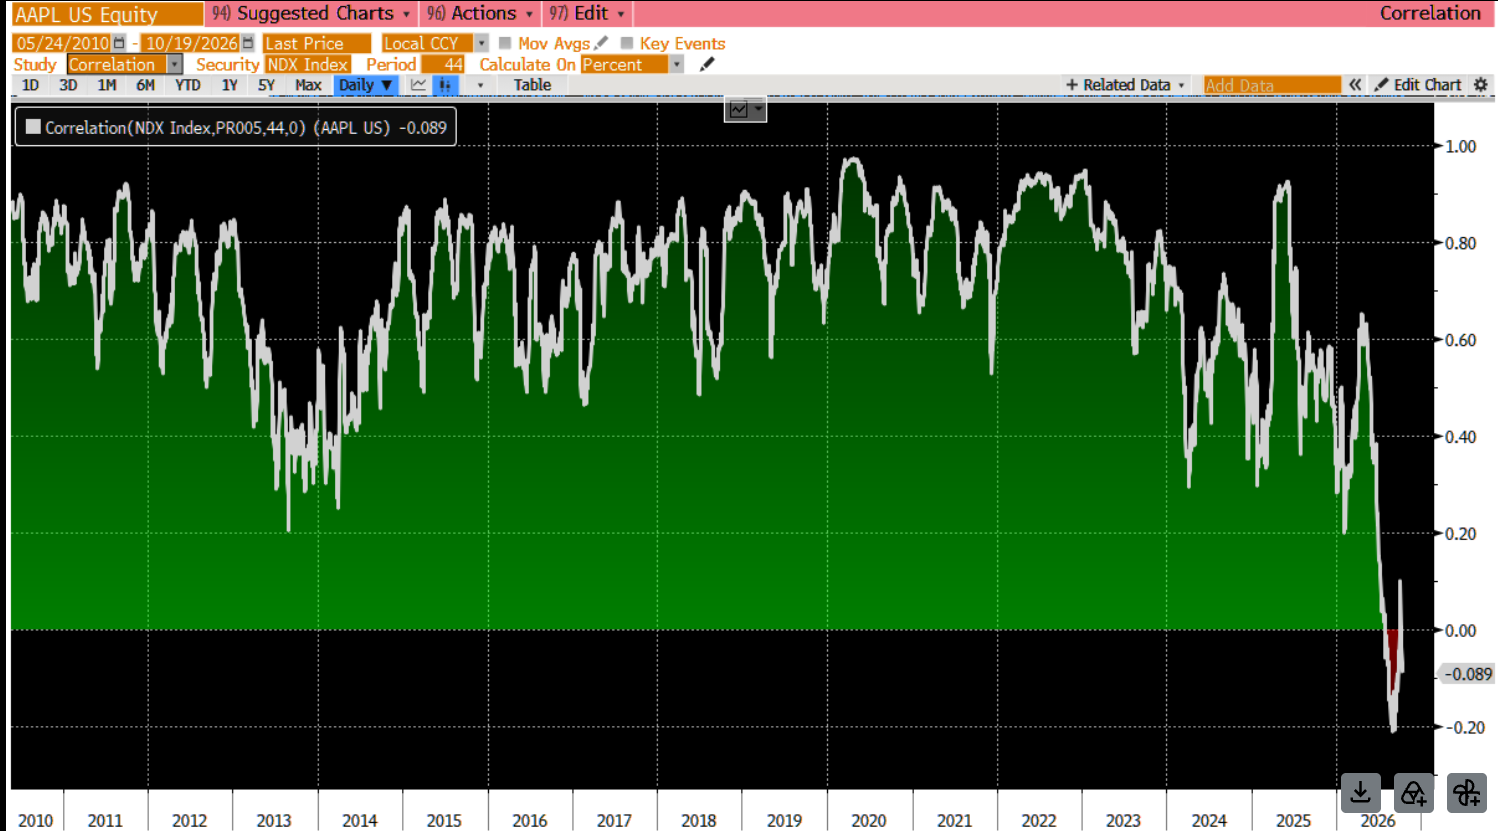
AAPL is trading near all-time highs, closing in on NVDA as the world's most valuable company. The stock has emerged as the ultimate defensive play within tech, with a forward FCF yield of around 3.15%, above that of the NDX.
The most striking development? Apple's rolling two-month correlation with the NDX has turned negative for the first time in history. A remarkable divergence that highlights the intensity of the flight to safety within tech. Full note here.
Source: GS/Bloomberg
Vive la périphérie
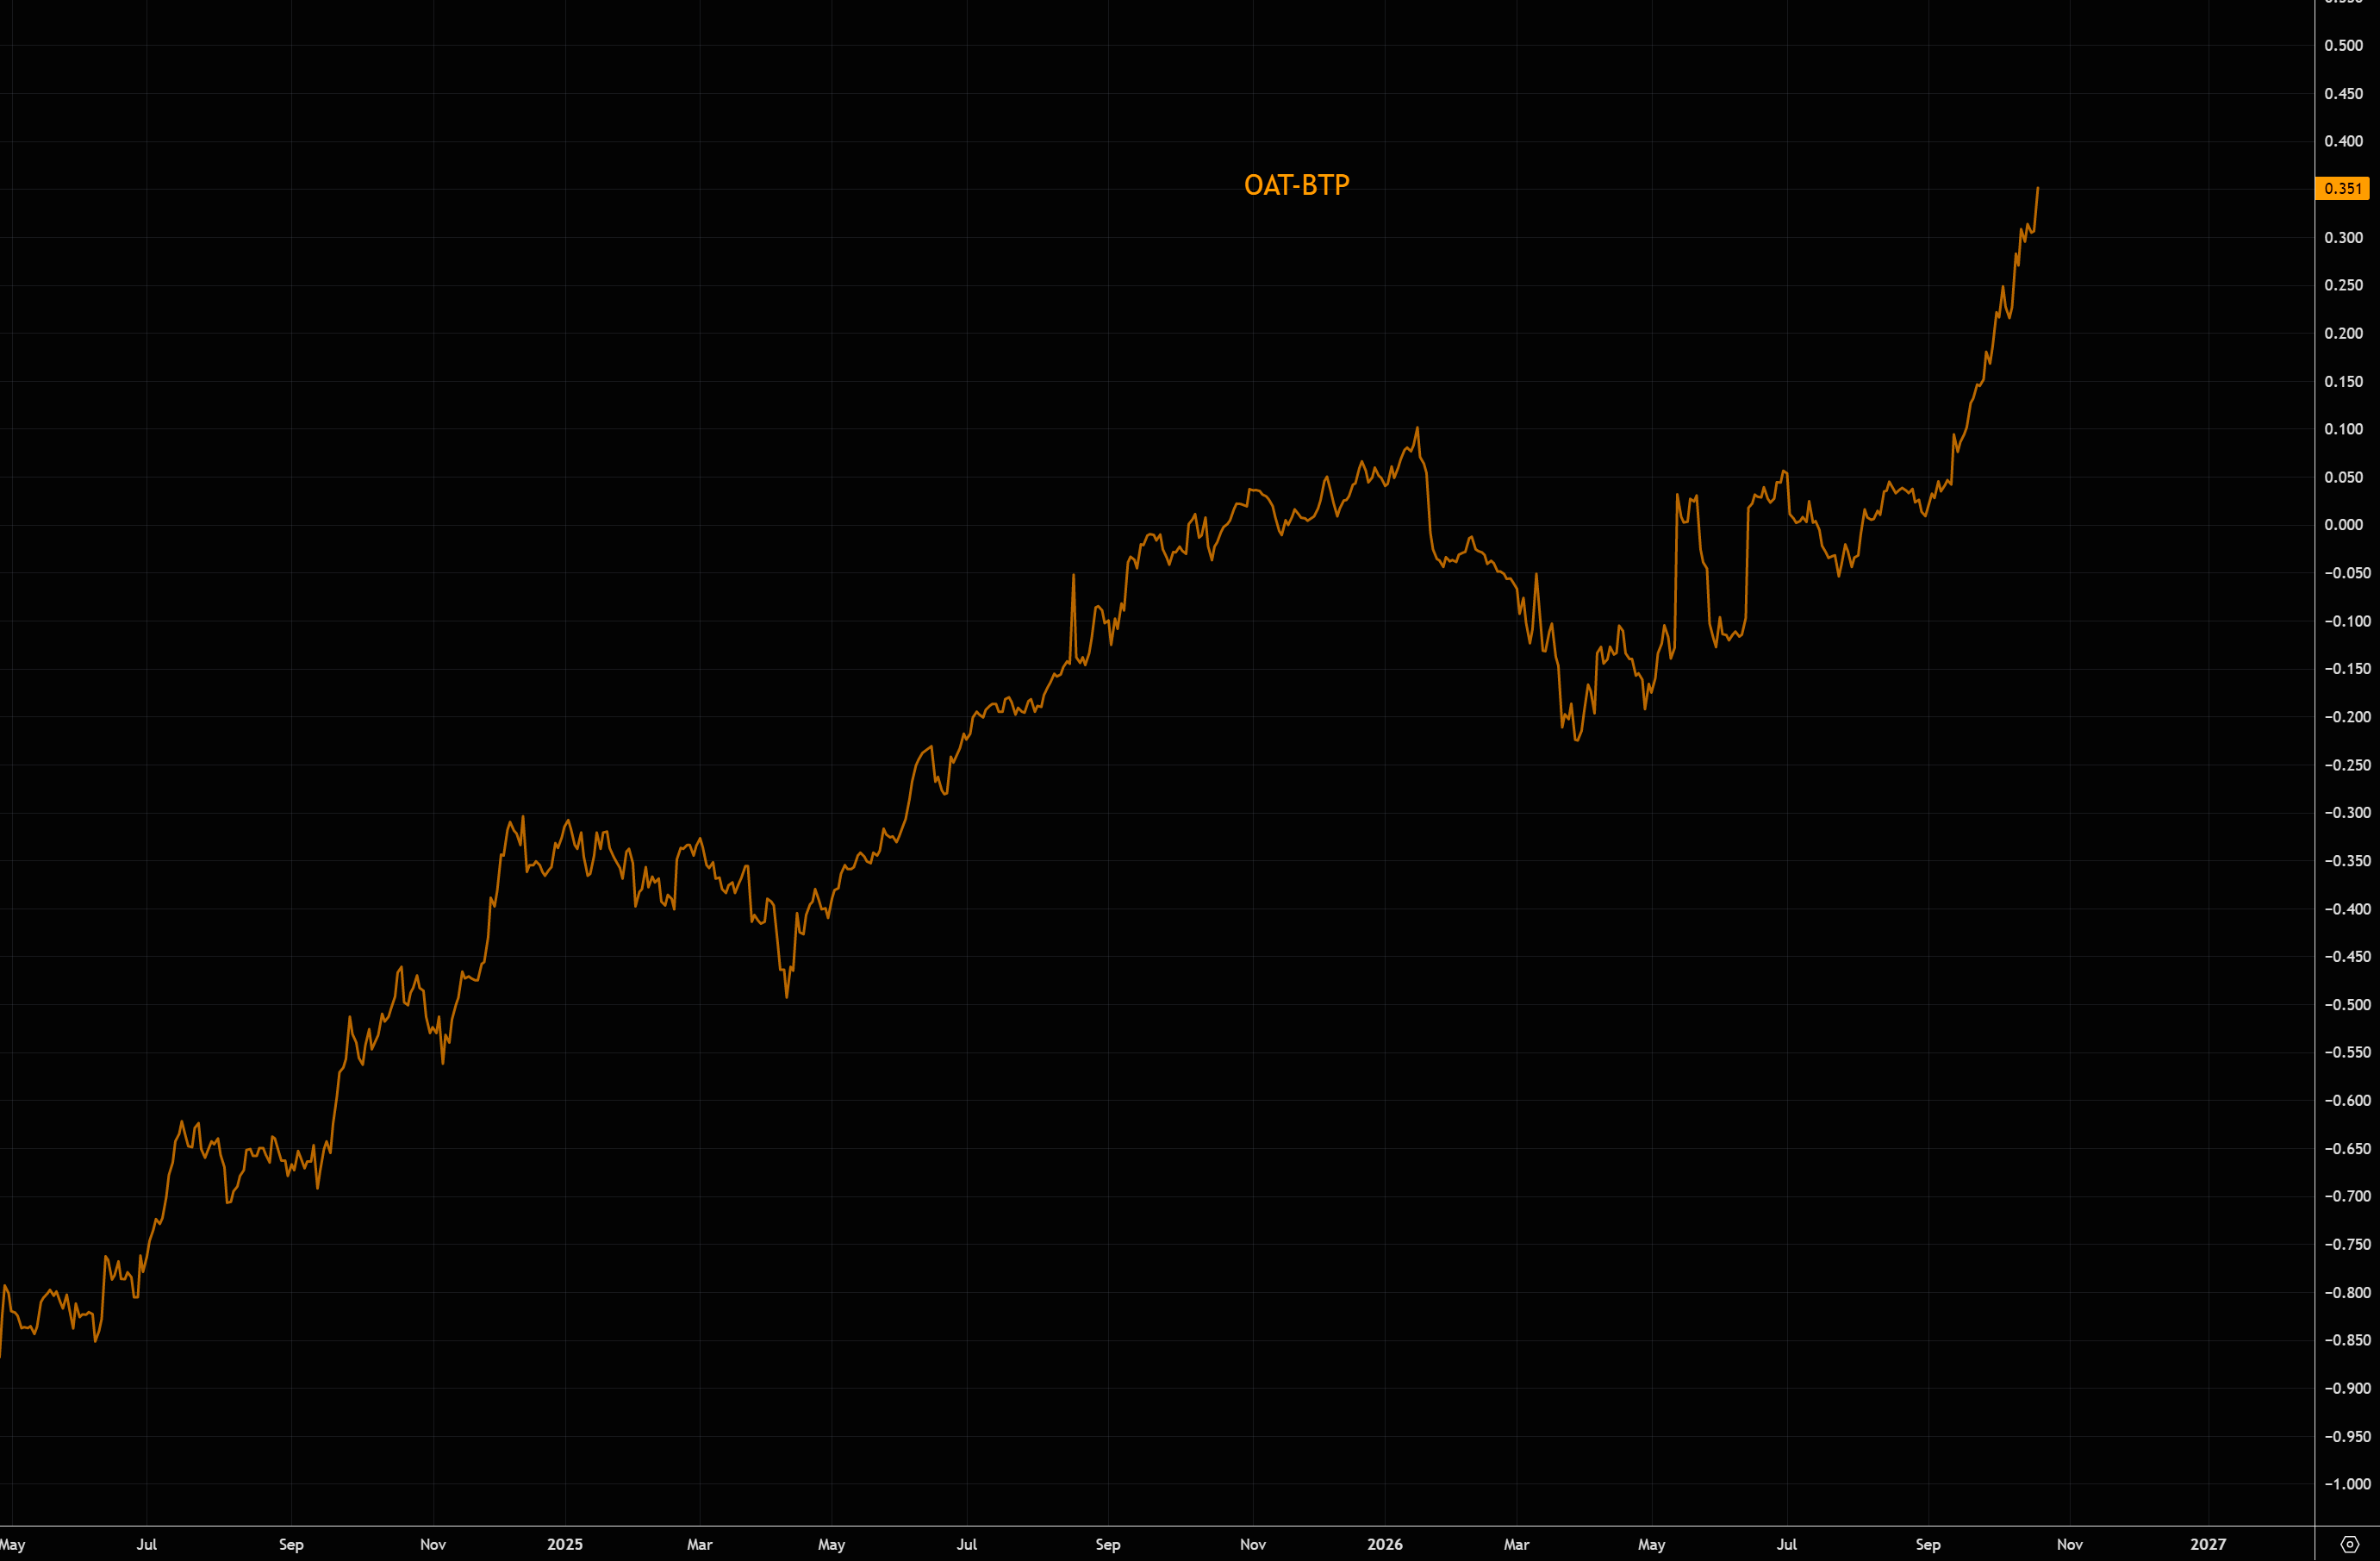
The European sovereign problem is increasingly becoming a France problem. The OAT-BTP spread continues marching higher, highlighting just how dramatically the market is redrawing Europe's traditional core/periphery divide. More on imploding France here.
Source: LSEG Workspace
Problem child
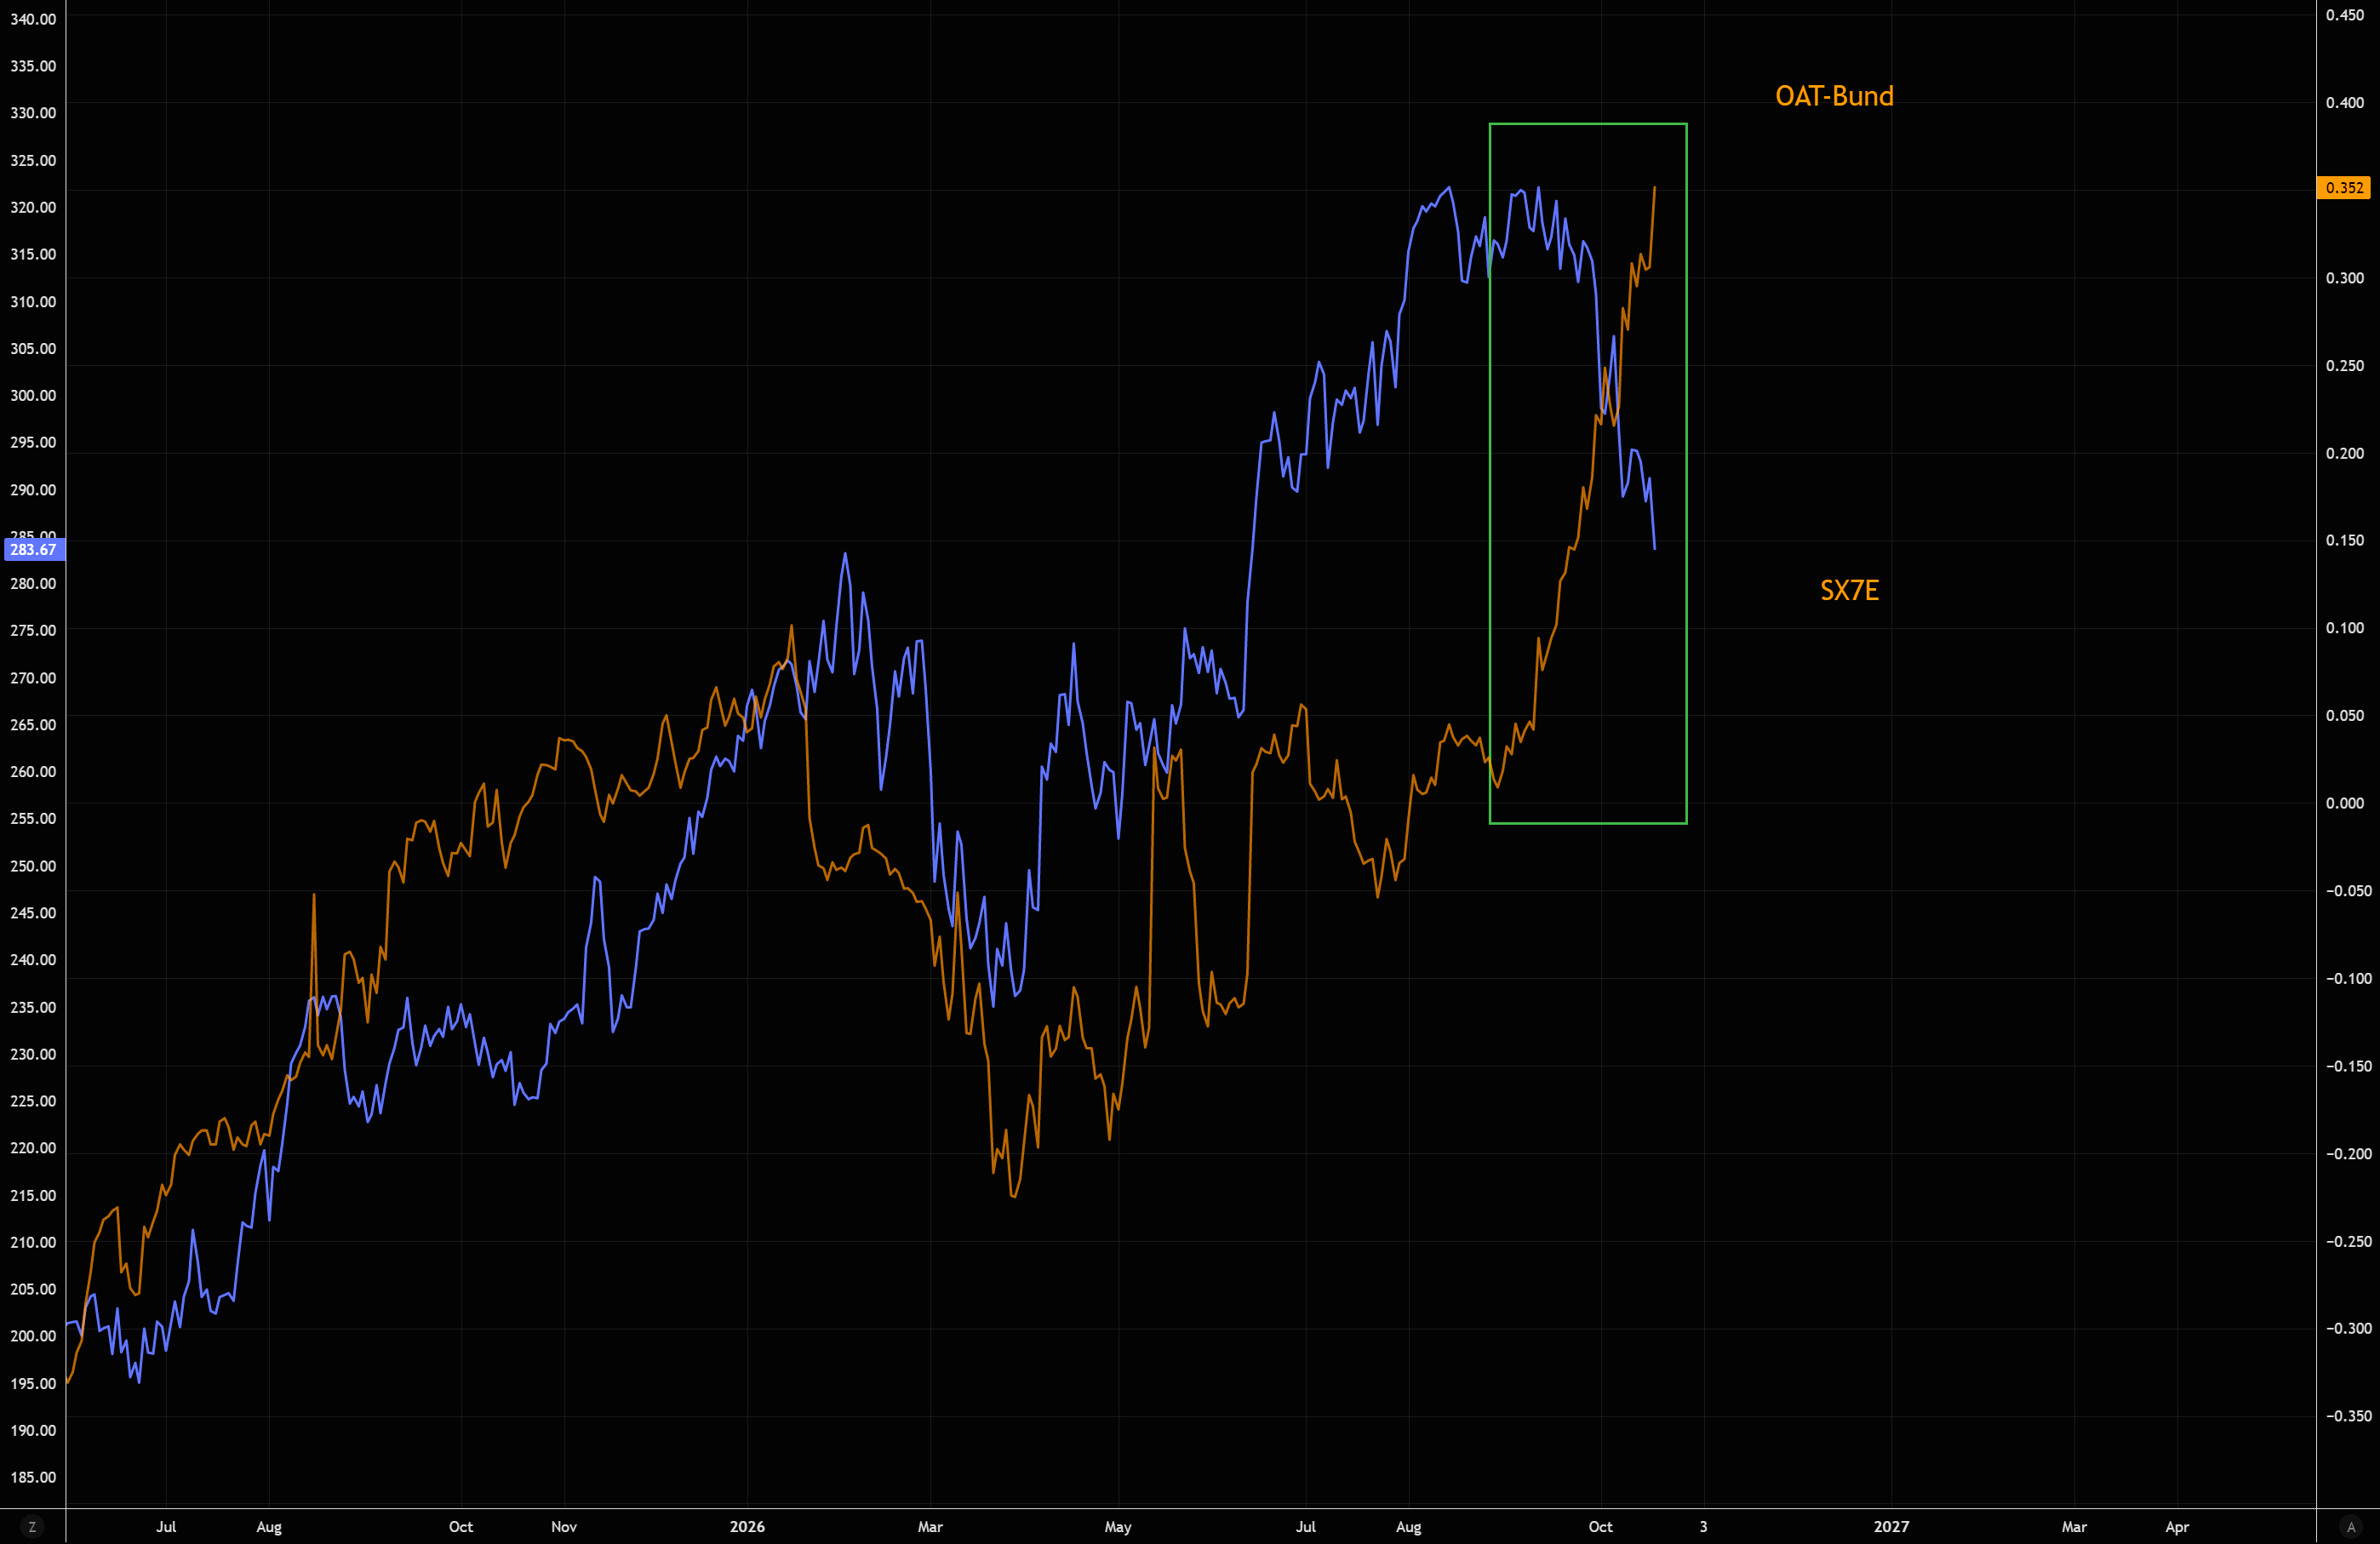
French 10-year yields now trade roughly 35bp above Italy. Think about that. France, once a core anchor of European sovereign debt, is increasingly trading like a peripheral credit.
The widening French-Italian yield spread is coinciding with a sharp selloff in European banks (SX7E). The sovereign stress is no longer just a bond market story. Bank equities are taking notice.
The old sovereign-bank doom loop doesn't need to return. Persistent sovereign stress alone could be enough to keep pressure on European banks.
We stick to our bearish SX7E logic outlined a few weeks ago (here).